What Happens When a Singapore Company Changes Its Share Capital After Incorporation?
A Comprehensive FAQ Guide to Share Capital Changes, ACRA Compliance, Shareholder Rights, Financial Implications and Business Growth in Singapore
Incorporating a Singapore Private Limited (Pte. Ltd.) company is only the beginning of its corporate journey. As a business develops, its funding needs, ownership structure, financial position and commercial priorities may change. The share capital established during incorporation may therefore need to be adjusted.
A company that starts with S$1, S$1,000 or S$10,000 in paid-up capital is not necessarily required to maintain that same capital structure throughout its existence. Depending on its circumstances, it may issue additional shares, receive outstanding share payments, reduce capital, reorganise existing shares or undertake other legally permitted capital transactions.
However, changing share capital after incorporation is not simply an accounting adjustment.
A share capital change may affect the company’s statutory records, shareholder rights, ownership percentages, financial statements, business relationships and regulatory obligations.
It is also important to understand that not every share capital transaction has the same consequences. For example, issuing new shares may dilute existing shareholders, while receiving payment for previously unpaid shares may increase paid-up capital without changing the number of issued shares.
Similarly, a transfer of existing shares changes ownership but does not, by itself, increase the company’s issued share capital.
This FAQ guide by ACHI BIZ SERVICES PTE. LTD., an ACRA Licensed Corporate Service Provider (CSP), explains what happens after a Singapore company changes its share capital, what directors and shareholders should expect, and which compliance matters deserve attention.
Unlike our separate articles covering the detailed procedures for increasing or reducing capital, this guide focuses primarily on the legal, financial, ownership, operational and compliance consequences of share capital changes after incorporation.
Understanding Share Capital Changes After Incorporation in Singapore
Can a Singapore Pte. Ltd. company change its share capital after incorporation?
Yes. A Singapore Pte. Ltd. company may change its share capital after incorporation, subject to the Companies Act 1967, its constitution, shareholder rights and other applicable legal requirements.
The company’s initial share capital is not necessarily permanent.
Businesses may adjust their capital structure to accommodate new investment, expansion, shareholder restructuring, financial difficulties or changes in business strategy.
However, the company must identify the correct legal transaction and complete the applicable corporate approvals and statutory filings.
What does changing share capital after incorporation actually mean?
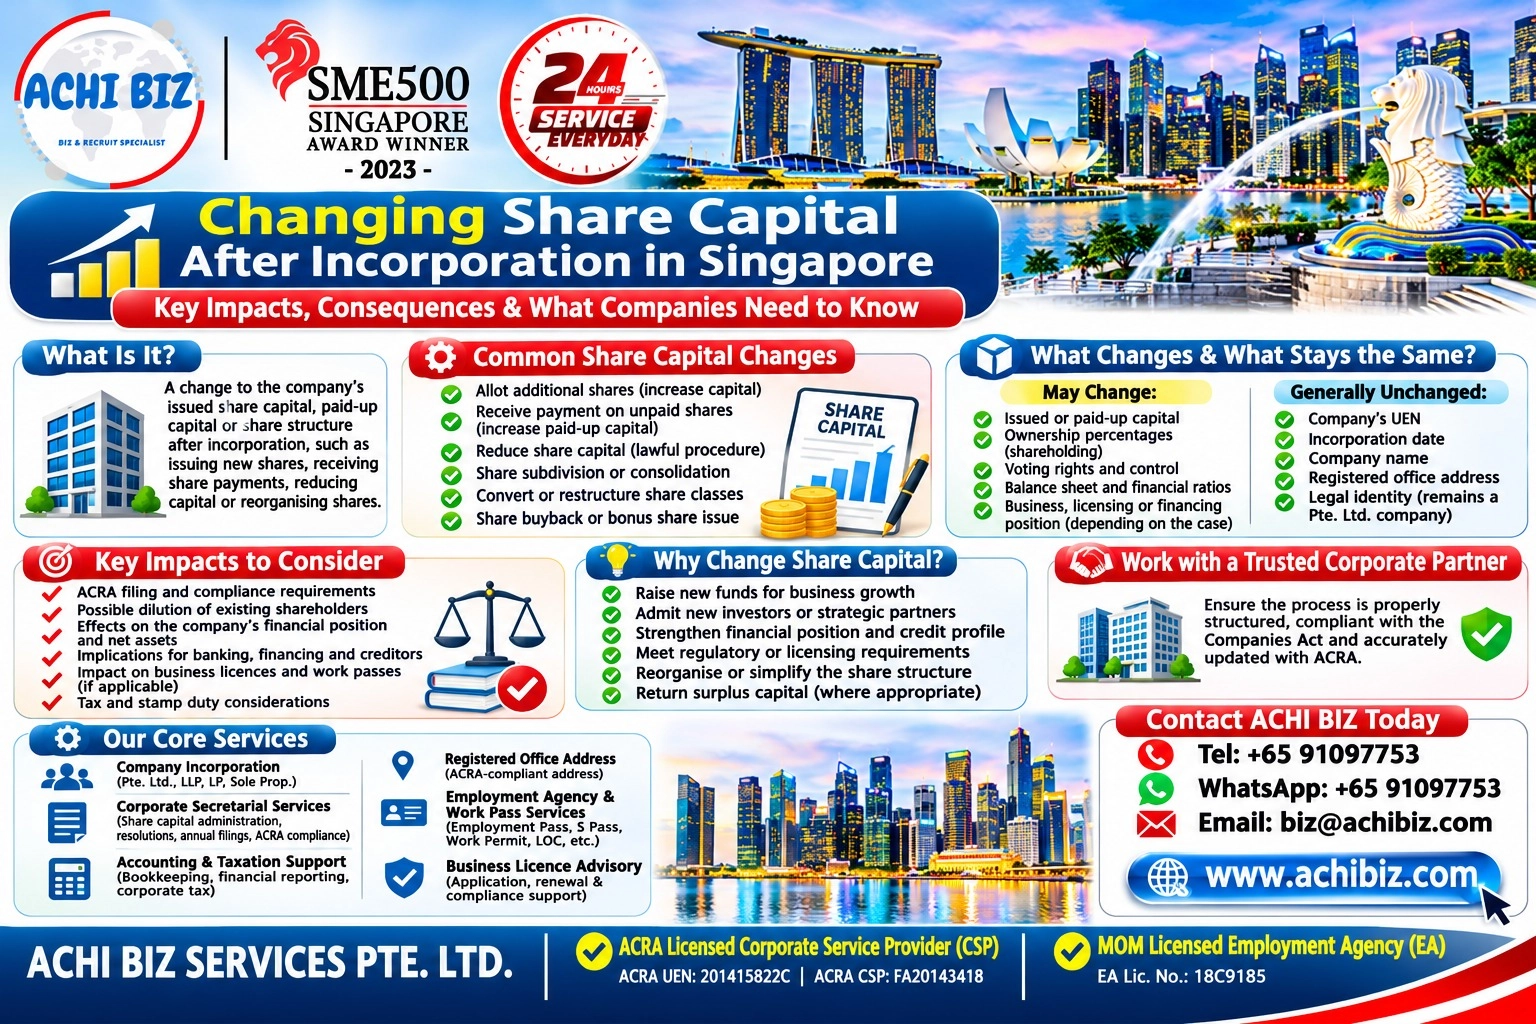
Changing share capital generally refers to a transaction that alters the company’s issued share capital, paid-up capital, unpaid share capital or the structure of its shares.
Examples include issuing additional shares, receiving payments on existing unpaid shares, reducing share capital, converting shares between classes where legally permitted, or reorganising shares.
Some transactions change the number of shares. Others change the capital amount without changing the number of shares.
The distinction matters because different transactions have different legal and financial consequences.
Is a share capital change the same as changing shareholders?
No.
A company can change its share capital without changing its shareholders, and it can change shareholders without changing its share capital.
For example, issuing additional shares to an existing shareholder may increase issued share capital while leaving the shareholder identities unchanged.
Conversely, transferring existing shares from one shareholder to another may change ownership without increasing the company’s issued share capital.
What types of share capital changes can occur after incorporation?
Common transactions include:
| Transaction | Possible effect |
|---|---|
| Allotment of additional shares | Increases issued shares and generally issued share capital |
| Payment of outstanding share amounts | Increases paid-up capital without necessarily issuing new shares |
| Capital reduction | Reduces share capital through a lawful procedure |
| Share subdivision | Increases the number of shares without necessarily changing total share capital |
| Share consolidation | Reduces the number of shares without necessarily changing total share capital |
| Conversion of share classes | Changes the nature or rights of shares, subject to applicable requirements |
| Share buyback | Company acquires its own shares under the statutory framework |
| Bonus share issue | May increase issued shares through a capitalisation arrangement |
| Share transfer | Changes ownership, but does not itself increase issued share capital |
The legal and accounting consequences depend on how each transaction is structured.
Does every share capital change increase the company’s paid-up capital?
No.
An allotment of fully paid shares may increase paid-up capital, but an allotment of partly paid shares may create an unpaid amount.
A subdivision or consolidation may change the number of shares without increasing the total capital contributed.
A reduction of share capital may decrease the recorded capital amount.
Therefore, companies should not treat every share-related transaction as an increase in paid-up capital.
Can a company change its share capital more than once after incorporation?
Yes.
A company may undertake multiple lawful share capital transactions throughout its existence.
For example, it may raise capital during expansion, reorganise its share structure when admitting investors and later reduce surplus capital.
Each transaction must be assessed independently for its approvals, documentation, filing requirements and financial implications.
Is there a maximum number of times a Singapore company can change its share capital?
There is no general fixed lifetime limit on the number of lawful share capital changes a Singapore company may undertake.
However, each transaction must comply with the applicable requirements.
Repeated changes without a genuine commercial purpose may also raise practical concerns for shareholders, banks, investors or regulators.
Does changing share capital mean the company must be incorporated again?
No.
A lawful change in share capital does not normally create a new legal entity.
The company continues operating under its existing registration and Unique Entity Number (UEN).
Its incorporation date and corporate identity remain unchanged.
Does the company’s UEN change when its share capital changes?
No.
A company’s UEN ordinarily remains the same following a share capital change.
The UEN identifies the registered legal entity, rather than the amount of capital it has issued or received.
Does changing share capital affect the company’s legal status as a Pte. Ltd. company?
Not automatically.
A Singapore private company generally remains a private company following a share capital change, provided it continues to satisfy the applicable legal requirements.
However, transactions affecting shareholder numbers, share transfer restrictions or other private-company conditions may require further consideration.
What Happens to ACRA Records After a Share Capital Change?
Must a Singapore company notify ACRA when its share capital changes?
For transactions that require statutory notification or registration, yes.
The company must complete the applicable filing through ACRA’s Bizfile system within the relevant statutory timeframe.
Different share capital transactions have different filing requirements.
A company should not assume that a single generic filing covers every type of capital change.
What happens to the company’s ACRA business profile after changing share capital?
Once the relevant transaction has been properly registered and processed, the company’s share capital information may be reflected in its ACRA records.
The precise information displayed depends on the type of filing and the particulars maintained by ACRA.
The company should obtain updated records where necessary and verify that the information is accurate.
Will ACRA automatically update the company’s shareholding percentages?
Relevant shareholding information is updated through the applicable statutory processes.
However, the company and its appointed corporate service provider remain responsible for ensuring that the underlying transaction details are accurate.
They should verify the number of shares held by each shareholder and the rights attached to those shares.
Does ACRA need to be notified if shareholders pay outstanding amounts on existing shares?
The company must comply with the applicable requirements for recording and notifying changes in paid-up share capital.
The transaction should be supported by appropriate evidence of payment and accurate corporate records.
This is different from issuing additional shares.
Is an ACRA filing required when a company subdivides or consolidates its shares?
Applicable statutory filing requirements must be followed when a company undertakes a subdivision or consolidation.
The company should also confirm that the transaction has been validly authorised.
What happens if the company fails to file a required share capital change with ACRA?
Failure to complete required filings may result in inaccurate statutory records and potential regulatory consequences.
It can also create practical difficulties when the company deals with banks, auditors, investors, prospective buyers or licensing authorities.
Where a filing is late or incorrect, the company should establish the appropriate corrective procedure.
Can a company correct an incorrectly reported share capital amount?
Potentially.
However, the correction method depends on the nature of the error.
A genuine filing mistake should not be confused with an attempt to reverse a legally effective share capital transaction.
The company should review its supporting documents and seek appropriate professional assistance.
Can a company backdate a share capital change?
The company must accurately record the relevant legal events and their actual dates.
It should not fabricate or backdate resolutions, payments, allotments or filings.
Where a transaction occurred earlier but was not properly reported, the company should obtain advice on the appropriate regularisation process.
Does changing share capital require updating the company’s statutory registers?
Yes, where the transaction affects particulars maintained in the company’s statutory registers.
For private companies, ACRA’s electronic register of members is particularly important, and the company must ensure the applicable registration requirements are met.
Other corporate records should also be reviewed and updated where relevant.
Does the company need to issue new share certificates after changing its share capital?
That depends on the transaction and the applicable statutory requirements.
A new allotment, subdivision, consolidation or other restructuring may require the issue or replacement of share certificates.
A payment against existing unpaid shares does not necessarily require an entirely new share certificate in every circumstance.
The company should ensure its share certificates and records remain consistent.
Does changing share capital affect the company’s annual return?
It may affect the information that must be accurately reflected in the company’s annual return and supporting records.
However, transaction-specific statutory filings should not be postponed simply because the annual return is due later.
Does a share capital change affect the company’s financial year-end?
No, not automatically.
The company’s financial year-end is a separate corporate matter.
A share capital change may affect financial reporting within the relevant accounting period, but it does not ordinarily change the financial year-end.
What Happens to Shareholders and Ownership Percentages?
Does changing share capital automatically change shareholders’ ownership percentages?
No.
The effect depends on the transaction.
For example, if two shareholders receive additional shares in the same proportions as their existing holdings, their percentage ownership may remain unchanged.
However, issuing shares disproportionately may change their ownership percentages.
Can existing shareholders lose ownership percentage after a capital increase?
Yes.
Where additional shares are issued to another shareholder or investor, existing shareholders may experience dilution.
Dilution means that a shareholder’s percentage of the total issued shares decreases, even though the number of shares they personally hold remains unchanged.
Can a shareholder’s ownership percentage increase without buying shares from another shareholder?
Yes.
For example, a shareholder may receive newly issued shares while other shareholders do not subscribe.
Their percentage ownership may consequently increase.
However, the allotment must comply with the company’s legal and contractual requirements.
Can a company increase share capital without diluting existing shareholders?
Potentially.
A proportionate allotment to existing shareholders may preserve their relative ownership percentages.
Alternatively, receiving outstanding payment on existing shares may increase paid-up capital without changing the number of issued shares.
Does a capital reduction automatically reduce everyone’s ownership percentage?
No.
A proportionate reduction may leave relative ownership percentages unchanged.
A selective transaction may have different consequences.
The company must consider the rights of affected shareholders and the applicable statutory requirements.
Can shareholders retain the same number of shares after a share capital change?
Yes.
For example, receiving payment on unpaid shares may increase paid-up capital without changing the share count.
A capital reduction may also be structured without cancelling shares, depending on the legal mechanism.
Does changing share capital affect voting rights?
Potentially.
Voting rights depend on the company’s share classes, constitution and relevant legal arrangements.
A transaction that changes the distribution or classes of voting shares may affect shareholder control.
However, increasing paid-up capital on existing shares does not necessarily change voting rights.
Can a minority shareholder lose influence after new shares are issued?
Yes.
Even where a minority shareholder retains the same number of shares, their relative voting influence may decline following a disproportionate allotment.
This can affect their ability to influence shareholder resolutions and other corporate decisions.
Can changing share capital affect control of the board of directors?
Potentially.
A change in ownership or voting rights may influence the ability to appoint or remove directors, subject to the company’s constitution, shareholders’ agreements and applicable law.
However, changing capital does not automatically replace existing directors.
Can changing share capital affect the company’s beneficial ownership records?
Yes, where the transaction changes beneficial ownership or control.
The company should assess whether its register of registrable controllers and related compliance records require updating.
The applicable statutory requirements must be followed.
Can a shareholder dispute arise after a share capital change?
Yes.
Disputes may arise over valuation, dilution, subscription rights, voting control, preferential treatment or the fairness of a transaction.
Companies should address these issues before implementing a material change.
Can a shareholder challenge a share capital change?
Potentially.
The available remedies depend on the facts, the company’s constitution, contractual rights and applicable law.
For example, an improperly authorised allotment or a transaction involving unfair prejudice may give rise to legal issues.
Does changing share capital affect shareholder agreements?
Potentially.
Shareholders’ agreements may contain provisions concerning new share issues, reserved matters, consent rights, dilution protection, valuation or exit arrangements.
A company should review these provisions before proceeding.
Does a share capital change automatically amend a shareholders’ agreement?
No.
A corporate transaction does not necessarily amend an existing contractual agreement.
Where amendments are required, the relevant parties should follow the agreement’s amendment provisions.
Financial and Accounting Consequences of Changing Share Capital
What happens to a Singapore company’s balance sheet when its share capital changes?
A share capital change may affect the equity section of the company’s balance sheet, its assets, liabilities or a combination of these items.
For example, where a company issues fully paid shares for cash, its cash balance and share capital generally increase.
Where it receives payment for previously unpaid shares, cash increases and the outstanding subscription amount is settled, with the accounting presentation depending on the original recognition of the subscription.
Where the company lawfully returns capital in cash, its share capital and cash balance generally decrease.
However, some share reorganisations do not change the company’s total assets or overall equity.
Does increasing issued share capital automatically increase the company’s cash balance?
No.
The company may issue shares for non-cash consideration, including eligible assets or the settlement of an existing debt.
Shares may also be issued on partly paid terms.
Therefore, an increase in issued share capital does not necessarily mean that an equivalent amount of new cash has entered the company’s bank account.
Can a company change its share capital without receiving any additional money?
Yes.
Certain capital transactions may be completed without receiving new cash.
Examples include a properly structured debt-to-equity conversion, bonus share issue or share subdivision.
The legal and accounting consequences differ between these arrangements.
Does a share capital increase automatically improve the company’s financial strength?
No.
The financial impact depends on what the company receives in exchange for the additional shares and how the transaction affects its liabilities.
An injection of genuine working capital may strengthen liquidity.
However, a non-cash capital transaction may not provide additional funds for daily operations.
Similarly, a company with substantial accumulated losses may remain financially weak despite having a relatively high share capital figure.
Does changing share capital affect the company’s net assets?
Potentially.
A fresh cash subscription generally increases the company’s net assets, assuming there are no offsetting liabilities or transaction effects.
A cash-funded capital return generally decreases net assets.
A subdivision or consolidation of shares normally does not change net assets merely because the number of shares changes.
Does increasing share capital eliminate accumulated losses?
No.
An increase in share capital does not automatically erase historical losses.
For example, a company may have S$500,000 in share capital and S$450,000 in accumulated losses.
Its total equity may be substantially lower than the share capital figure suggests.
A capital restructuring involving accumulated losses is a separate matter that must be evaluated according to its legal and accounting treatment.
Can changing share capital affect the company’s working capital?
Yes.
A cash injection may improve working capital by increasing current assets.
Conversely, returning cash to shareholders may reduce the funds available for operations.
However, a share transaction that involves only a reclassification within equity may have no immediate working capital effect.
Does changing share capital affect the company’s debt-to-equity ratio?
Potentially.
Suppose a company has S$300,000 in liabilities and S$100,000 in total equity.
Its debt-to-equity ratio is 3:1.
If a fresh capital injection increases total equity to S$200,000 while liabilities remain unchanged, the ratio becomes 1.5:1.
This may improve certain financial indicators, although lenders will assess more than one ratio.
Can a share capital change improve the company’s creditworthiness?
Potentially.
A genuine injection of funds may strengthen liquidity and reduce financial risk.
However, lenders and commercial creditors may also examine profitability, cash flow, existing borrowings, payment history and the financial position of shareholders or guarantors.
Higher share capital alone does not guarantee better creditworthiness.
Does changing share capital affect the company’s profit and loss statement?
A genuine share capital transaction is generally recorded within equity rather than treated as ordinary business revenue or operating expenditure.
However, associated professional fees, transaction costs and other items may require separate accounting treatment under the applicable accounting standards.
Does a company need to prepare new financial statements immediately after changing share capital?
Not necessarily.
A share capital change does not ordinarily require the company to prepare an entirely new set of annual financial statements immediately.
Nevertheless, the company should maintain accurate accounting records and reflect the transaction in the appropriate reporting period.
Banks, investors or other parties may request updated management accounts.
Does changing share capital affect the company’s audit requirements?
Not automatically.
A company’s audit exemption eligibility depends on the applicable statutory criteria.
A change in share capital alone does not necessarily make the company subject to a statutory audit.
However, the transaction may affect the company’s financial position or group structure, which could be relevant to broader compliance assessments.
Can share capital changes affect financial statement disclosures?
Yes.
Depending on the transaction and applicable accounting framework, disclosures may be required concerning issued shares, share classes, movements in share capital and related rights.
Material transactions should be appropriately reflected in the company’s financial records.
Can changing share capital affect the company’s ability to distribute dividends?
Potentially.
A fresh capital injection may provide cash, but cash availability does not by itself establish that dividends can legally be paid.
Under Singapore company law, dividends are generally payable only out of profits.
Similarly, a capital reduction may affect the company’s resources available for future distributions.
Can a company use newly contributed share capital to pay business expenses?
Generally, yes.
Once lawfully received, share subscription funds become company assets and may be used for legitimate business purposes, subject to applicable restrictions and obligations.
The company is not ordinarily required to keep the original subscription amount permanently untouched in its bank account.
Does a change in share capital mean the company’s business is making a profit?
No.
Share capital reflects equity funding and related capital transactions, not necessarily operating profitability.
A company may raise substantial capital while continuing to make losses.
Conversely, a profitable company may operate with relatively modest paid-up capital.
Business Operations and Commercial Consequences
Does changing share capital affect the company’s daily business operations?
Not necessarily.
A properly completed capital transaction may have little immediate effect on daily operations.
However, the financial or ownership consequences may influence the company’s business decisions.
For example, additional funding may support recruitment, equipment purchases, expansion or new projects.
A reduction in available capital may require tighter expenditure controls.
Can changing share capital affect existing customer contracts?
Potentially.
Some contracts contain provisions relating to financial condition, ownership changes, minimum net worth or notification obligations.
A share capital change does not automatically invalidate existing customer contracts, but the company should review relevant contractual terms.
Does changing share capital affect existing supplier agreements?
Potentially.
Suppliers may have credit arrangements or contractual conditions based on the company’s financial position.
A material capital reduction or ownership restructuring could prompt a review of credit terms.
However, an ordinary capital increase may have no effect on existing supplier agreements.
Can a share capital change affect the company’s trade credit limit?
Yes, potentially.
Suppliers may consider updated financial information when assessing credit exposure.
An increase in actual financial resources could support a stronger credit application, but approval remains at the supplier’s discretion.
Does changing share capital affect existing business loans?
It may.
Loan agreements sometimes contain restrictions concerning distributions, changes in control, additional equity, financial covenants or capital restructuring.
The company should review its financing documents before undertaking a material transaction.
Can a bank require notification when a company changes its share capital?
Yes, depending on the bank’s requirements and the nature of the transaction.
Banks may request updated corporate records, ownership information, financial statements or beneficial ownership declarations.
Does changing share capital require opening a new corporate bank account?
No, not ordinarily.
A share capital change does not automatically require a company to open a new bank account.
However, the bank may request updated corporate information.
Can a capital increase affect the company’s eligibility for business financing?
Potentially.
Additional equity funding may improve certain financial ratios and demonstrate shareholder commitment.
However, banks may still require financial statements, cash-flow projections, security, guarantees and other supporting documents.
Can a capital reduction affect the company’s financing arrangements?
Yes.
A capital reduction involving a distribution of assets may weaken liquidity or reduce equity.
It may also affect financial covenants or contractual restrictions.
The company should assess these consequences before implementing the transaction.
Does changing share capital affect the company’s ability to purchase commercial property?
Potentially.
Additional capital may help fund deposits, acquisition costs or working capital.
However, property financing depends on the lender’s requirements, the company’s financial position and the proposed transaction.
Can changing share capital affect a commercial tenancy agreement?
Potentially.
Landlords may consider financial strength, security deposits, guarantees or changes in corporate control.
The company should review its lease terms where a material restructuring is proposed.
Can changing share capital improve business credibility?
It may influence how certain customers, suppliers, investors or financial institutions perceive the company.
However, share capital is only one indicator.
Business performance, financial stability, contractual reliability and compliance history remain important.
Does a share capital change affect the company’s business name or registered address?
No, not automatically.
The company’s name and registered office address are separate registered particulars.
They remain unchanged unless the company undertakes the relevant procedures to change them.
Does changing share capital require a company to stop trading temporarily?
Not ordinarily.
A company can generally continue its business activities while completing an appropriately managed capital transaction.
However, certain complex transactions may involve conditions, approvals or restrictions that affect implementation.
Employment Pass, Business Licensing and Regulatory Considerations
Does changing share capital affect a Singapore company’s Employment Pass holders?
Not automatically.
A lawful share capital change does not, by itself, mean that existing Employment Passes are cancelled.
However, the employer must continue meeting the applicable Ministry of Manpower requirements.
Changes affecting the employer’s actual operations, ownership or financial circumstances may warrant further review.
Does increasing paid-up capital guarantee Employment Pass approval?
No.
There is no universal rule that increasing a company’s paid-up capital to a particular amount guarantees Employment Pass approval.
Applications are assessed against the applicable MOM criteria.
A company’s financial and operational circumstances may be relevant, but share capital alone does not determine the outcome.
Can a reduction in share capital affect future work pass applications?
Potentially.
Where a capital reduction materially weakens the employer’s financial position or affects its business operations, those circumstances may become relevant to an assessment.
However, a capital reduction does not automatically result in refusal.
Does changing share capital affect existing S Pass or Work Permit holders?
Not automatically.
The company must continue complying with the relevant employment, quota, levy, security and other applicable requirements.
Any changes affecting the employer’s eligibility or operating circumstances should be assessed separately.
Can changing share capital affect a company’s business licence?
Yes, where the relevant licensing regime imposes capital, financial resource, ownership or other continuing requirements.
A company should identify these requirements before implementing a capital transaction.
Does every Singapore business licence require a minimum paid-up capital?
No.
Requirements vary by industry and licensing authority.
Some regulated activities have specific financial requirements, while others do not impose a universal paid-up capital threshold.
Can a company increase its capital to satisfy a licensing requirement?
Potentially.
However, the company must verify the precise requirement.
A regulator may distinguish paid-up share capital from net assets, working capital, security deposits, financial resources or other eligibility criteria.
Increasing the registered capital figure may not be sufficient if the requirement concerns something else.
Can reducing capital cause a company to breach licensing conditions?
Yes, potentially.
Where the company must maintain a prescribed capital or financial threshold, a reduction could create a compliance problem.
The company should review the relevant licence conditions before proceeding.
Can an ACRA Licensed Corporate Service Provider (CSP) change its share capital?
Yes, subject to the applicable legal requirements.
The provider must also consider whether the transaction affects its ownership, controllers or other matters subject to regulatory notification or approval.
Can a MOM Licensed Employment Agency (EA) change its share capital?
Potentially.
However, the agency must consider applicable licensing requirements and whether the transaction affects any relevant financial, ownership or regulatory conditions.
Does changing share capital affect government tender eligibility?
Potentially.
Some government procurement arrangements, registrations or tender specifications include financial or corporate eligibility criteria.
A share capital change may be relevant where those criteria specifically refer to capital or financial resources.
Can a company increase its capital solely to qualify for a tender?
A company may consider a genuine capital injection to support its business needs.
However, it must satisfy the tender’s actual eligibility requirements.
A higher paid-up capital figure does not automatically qualify a company for every tender.
Does changing share capital affect GST registration?
Not automatically.
GST registration is generally determined by the applicable taxable turnover rules and other relevant conditions, rather than the company’s share capital alone.
Does changing share capital affect corporate income tax registration?
A share capital change does not ordinarily create a new company or a new UEN.
The company remains responsible for its existing corporate income tax obligations.
Does changing share capital affect the company’s CPF obligations?
Not automatically.
CPF obligations depend on the relevant employment arrangements and statutory requirements.
However, a capital transaction that accompanies an operational restructuring may have separate employment consequences.
Tax and Stamp Duty Implications of Share Capital Changes
Is a capital increase taxable income for a Singapore company?
A genuine share subscription is generally an equity funding transaction rather than ordinary taxable business income.
However, the tax treatment depends on the actual legal and commercial nature of the arrangement.
Does a company pay corporate income tax simply because its share capital increases?
Generally, no.
Increasing share capital does not itself mean the company has earned taxable profits.
Is stamp duty payable when a Singapore company issues new shares?
A straightforward allotment of new shares is generally not treated in the same way as a transfer of existing shares for stamp duty purposes.
However, the company should assess whether the transaction includes other dutiable instruments or arrangements.
Is stamp duty payable when existing shares are transferred?
Share transfers may attract Singapore stamp duty, subject to the applicable rules, exemptions and reliefs.
This is one reason why companies must distinguish an allotment of new shares from a transfer of existing shares.
Can a share capital restructuring have tax consequences for shareholders?
Yes, potentially.
The consequences depend on the transaction and the shareholder’s circumstances.
For example, a share transfer, capital repayment, debt conversion or corporate restructuring may have different tax implications.
Does a bonus share issue automatically create taxable income for shareholders?
Not necessarily.
The tax treatment depends on the nature of the bonus issue and the relevant circumstances.
The company should not assume that every bonus issue has the same tax treatment.
Can a debt-to-equity conversion have tax consequences?
Yes, potentially.
The conversion may involve the settlement of a liability, the issue of shares and other financial or tax considerations.
The company should assess the original debt, its accounting treatment and the commercial substance of the arrangement.
Does reducing share capital automatically create a tax deduction?
No.
A reduction in share capital is not ordinarily an operating expense simply because the recorded capital amount decreases.
Does changing share capital affect the company’s tax losses?
Not automatically.
However, changes in share ownership may be relevant to statutory shareholding tests governing the utilisation of certain tax losses and other tax attributes.
Companies undertaking substantial ownership changes should assess these rules carefully.
Can changes in shareholders affect the utilisation of unabsorbed capital allowances?
Potentially.
Singapore’s rules concerning the carry-forward and utilisation of unabsorbed capital allowances include relevant conditions.
A change in ownership should therefore be considered alongside the company’s tax position.
Does changing share capital require notifying IRAS?
Not every capital transaction requires a separate notification to IRAS solely because the share capital amount changes.
However, the company must comply with applicable tax filing, stamp duty and reporting obligations.
The requirements depend on the transaction.
Changes to Share Classes, Rights and Corporate Governance
Can a Singapore company introduce a new class of shares after incorporation?
Yes, subject to the Companies Act, the company’s constitution and applicable approvals.
A company may consider different share classes to accommodate investment, voting arrangements or commercial objectives.
However, the rights attached to each class must be properly established and documented.
Does introducing preference shares automatically increase paid-up capital?
Not necessarily.
The financial effect depends on whether new preference shares are issued, the consideration payable and the amount actually paid.
Creating or altering share rights is not the same as receiving additional cash.
Can a company change ordinary shares into preference shares?
Potentially, where the relevant legal and constitutional requirements permit the proposed conversion or restructuring.
The company must consider existing class rights, shareholder approvals and any applicable variation-of-rights requirements.
Can shareholders have different voting rights after a capital restructuring?
Yes, where the share structure lawfully provides for different voting rights.
However, changes affecting existing rights must comply with the applicable legal framework.
Can a company issue non-voting shares after incorporation?
Potentially.
The company must consider the Companies Act, its constitution and the relevant rights attached to the proposed shares.
Does changing share classes affect dividend entitlements?
Potentially.
Different share classes may carry different dividend rights.
For example, preference shares may have priority dividend rights, depending on their terms.
The company should ensure the rights are clearly documented.
Can changing share capital affect liquidation preferences?
Yes.
Where a company has multiple share classes, the rights attached to those shares may determine how available assets are distributed in a winding-up.
These rights should be considered before issuing or restructuring shares.
Can a company reorganise its shares without changing its total issued share capital amount?
Yes, potentially.
For example, a subdivision may increase the number of shares while leaving the aggregate issued share capital unchanged.
A consolidation may reduce the number of shares without necessarily reducing the aggregate capital amount.
Does a share subdivision make the company more valuable?
No.
A subdivision changes the number of shares, but it does not automatically increase the company’s total economic value.
For example, dividing 1,000 shares into 10,000 shares does not, by itself, make the underlying business worth ten times more.
Does a share consolidation reduce the company’s overall value?
Not automatically.
A consolidation changes the number of shares, but it does not necessarily change the company’s total equity or underlying economic value.
Can a share capital change affect future fundraising?
Yes.
Investors may examine the company’s existing share classes, ownership structure, outstanding subscription obligations and rights attached to its shares.
A complicated or poorly documented capital structure can make future fundraising more difficult.
Can a share capital change affect a future business sale?
Yes.
Prospective buyers commonly review the company’s capital history, shareholder records, share rights and compliance documents.
Unresolved discrepancies may delay due diligence or create concerns about ownership.
Does changing share capital affect the valuation of the company?
Not automatically.
The amount of share capital recorded in the company’s statutory records is not necessarily equal to the market value of the company.
Valuation may depend on profitability, assets, growth prospects, cash flow, commercial risks and other factors.
Can a company issue shares at a price different from the amount paid by its original shareholders?
Potentially.
Singapore operates under a no-par-value share regime, and new shares may be issued on commercially determined terms, subject to applicable legal requirements.
The company should consider valuation, existing shareholder rights, fairness and the appropriate approvals.
Can an investor pay S$100,000 for a small percentage of a company that originally had S$1,000 share capital?
Yes, potentially.
The amount an investor contributes and the ownership percentage received depend on the agreed valuation and transaction structure.
For example, an investor may subscribe S$100,000 for 10% of the enlarged share capital.
The company’s historical incorporation capital does not, by itself, determine the investment valuation.
Practical Examples of Share Capital Changes After Incorporation
The following examples are hypothetical and focus on the consequences of capital changes rather than the detailed statutory procedures.
Example 1: What happens when a company increases its capital from S$1,000 to S$100,000?
Suppose ABC Pte. Ltd. was incorporated with S$1,000 in fully paid ordinary share capital.
After two years, it decides to raise an additional S$99,000 through a fully paid allotment.
| Particulars | Before | After |
|---|---|---|
| Paid-up capital | S$1,000 | S$100,000 |
| Additional cash contributed | — | S$99,000 |
| Company UEN | Unchanged | Unchanged |
| Company incorporation date | Unchanged | Unchanged |
The company receives additional equity funding and may use it for legitimate business purposes.
Its legal identity remains unchanged.
However, the ownership consequences depend on who subscribes for the new shares.
Example 2: What happens when one shareholder subscribes for additional shares but another does not?
Suppose a company initially has 1,000 ordinary shares.
Shareholder A holds 600 shares, while Shareholder B holds 400.
The company then issues 500 additional ordinary shares to A.
| Shareholder | Original shares | New shares | Total shares | New ownership |
|---|---|---|---|---|
| A | 600 | 500 | 1,100 | 73.33% |
| B | 400 | 0 | 400 | 26.67% |
| Total | 1,000 | 500 | 1,500 | 100% |
Before the allotment, A owned 60% and B owned 40%.
Afterwards, B’s ownership decreases to approximately 26.67%, despite B retaining all 400 original shares.
This illustrates shareholder dilution.
Example 3: What happens when both shareholders subscribe proportionately?
Suppose the same company issues 1,000 additional shares, allocated according to the existing 60:40 ownership ratio.
| Shareholder | Original shares | Additional shares | Total shares | Ownership |
|---|---|---|---|---|
| A | 600 | 600 | 1,200 | 60% |
| B | 400 | 400 | 800 | 40% |
| Total | 1,000 | 1,000 | 2,000 | 100% |
The number of shares increases, but the relative ownership percentages remain unchanged.
Example 4: What happens when a company receives payment for previously unpaid shares?
Suppose a company has issued 100,000 ordinary shares for a total subscription consideration of S$100,000.
Only S$40,000 has been paid.
The shareholders subsequently pay the outstanding S$60,000.
| Particulars | Before payment | After payment |
|---|---|---|
| Issued shares | 100,000 | 100,000 |
| Total subscription consideration | S$100,000 | S$100,000 |
| Paid-up amount | S$40,000 | S$100,000 |
| Outstanding amount | S$60,000 | S$0 |
The paid-up amount increases without issuing additional shares.
The ownership percentages remain unchanged.
Example 5: What happens when a new investor subscribes S$200,000 for 20% ownership?
Suppose a company and investor agree that the investor will contribute S$200,000 for 20% of the company after the investment.
Assuming a straightforward fully paid cash allotment:
| Particulars | Amount |
|---|---|
| New investment | S$200,000 |
| Investor’s post-investment ownership | 20% |
| Implied post-money valuation | S$1,000,000 |
| Implied pre-money valuation | S$800,000 |
The company’s share capital increases by the applicable subscription amount.
The existing shareholders collectively retain 80% of the enlarged ordinary shareholding, assuming one class of equally ranking shares.
The implied valuation is a commercial calculation, not the same as the company’s registered share capital.
Example 6: What happens when a company converts a S$150,000 shareholder loan into equity?
Suppose a shareholder previously lent S$150,000 to the company.
The parties agree to convert the debt into share capital through a lawful allotment.
Assuming the full debt is validly settled in exchange for shares:
| Financial item | Before | After |
|---|---|---|
| Shareholder loan liability | S$150,000 | S$0 |
| Additional share capital | — | S$150,000 |
| New cash received at conversion | — | S$0 |
The company reduces its liabilities and increases equity.
However, it does not receive an additional S$150,000 in cash at the time of conversion.
Example 7: What happens when a company subdivides 1,000 shares into 10,000 shares?
Suppose the company has 1,000 ordinary shares representing S$100,000 in issued and fully paid share capital.
It undertakes a 10-for-1 subdivision.
| Particulars | Before | After |
|---|---|---|
| Number of shares | 1,000 | 10,000 |
| Aggregate share capital | S$100,000 | S$100,000 |
| Additional funds received | S$0 | S$0 |
| Total ownership percentages | 100% | 100% |
The share count increases tenfold, but the aggregate share capital does not increase merely because of the subdivision.
Example 8: What happens when a company consolidates 100,000 shares into 10,000 shares?
Suppose the company undertakes a 10-for-1 consolidation.
The total number of shares decreases, but the aggregate share capital may remain unchanged.
Existing shareholders may retain the same relative ownership percentages, subject to how fractional entitlements are dealt with.
Example 9: What happens when a company reduces share capital without cancelling shares?
Suppose a company has 100,000 shares representing S$200,000 in paid-up capital.
It completes a lawful S$50,000 capital reduction without cancelling shares.
| Particulars | Before | After |
|---|---|---|
| Issued shares | 100,000 | 100,000 |
| Paid-up capital | S$200,000 | S$150,000 |
| Shareholding percentages | Unchanged | Unchanged |
The company’s share count remains the same.
The financial consequences depend on whether the reduction involves a cash repayment, the cancellation of losses or another permitted arrangement.
Example 10: What happens when existing shares are transferred to a new shareholder?
Suppose a company has 10,000 fully paid ordinary shares and S$10,000 in paid-up capital.
Shareholder A transfers 2,000 existing shares to Shareholder C.
The company’s total issued shares and paid-up capital remain unchanged.
Only the ownership distribution changes.
This is an important distinction because the consideration paid for the transferred shares ordinarily goes to the selling shareholder, rather than becoming new capital contributed to the company.
Example 11: What happens when a company changes share capital but forgets to update its bank?
The bank’s records may become inconsistent with the company’s current corporate particulars.
The bank may request updated ACRA records, shareholder information or beneficial ownership documentation.
This can create administrative delays, particularly during financing applications or compliance reviews.
Example 12: What happens when a company reduces capital before applying for a regulated business licence?
Suppose a company reduces its capital and later discovers that its intended regulated activity requires a specified capital or financial threshold.
The company may need to obtain additional funding or restructure its finances before meeting the applicable eligibility requirements.
This illustrates why regulatory planning should take place before a material capital reduction.
Example 13: What happens when a company increases capital but continues to make operating losses?
Suppose a company has S$300,000 in paid-up capital but accumulated losses of S$250,000.
Ignoring other equity items, its total equity would be approximately S$50,000.
A larger paid-up capital figure does not eliminate the effect of historical losses.
The company should distinguish registered capital from actual net financial strength.
Example 14: What happens when a company issues shares shortly before being sold?
The new allotment may change the ownership percentages, rights and valuation assumptions relevant to the sale.
The buyer may request additional documentation and explanations.
A poorly coordinated allotment could complicate the transaction or create disagreements about the purchase price.
Example 15: What happens when a company changes share capital several times over five years?
The company may have a complex history involving multiple allotments, repayments, transfers and reorganisations.
It should maintain a clear record of each transaction, including its commercial purpose, approvals, supporting documents, effective dates and statutory filings.
This helps future shareholders, auditors, lenders and prospective buyers understand the company’s capital history.
Share Capital Changes and Corporate Compliance Responsibilities
Who is responsible for ensuring that a share capital change complies with Singapore law?
The company’s directors are responsible for ensuring that corporate decisions and transactions comply with their legal duties.
Shareholders must provide the approvals required by law, the constitution and applicable agreements.
The company secretary or appointed corporate service provider may assist with documentation and statutory filings.
However, engaging a professional service provider does not eliminate directors’ legal responsibilities.
Can directors change share capital without consulting shareholders?
Not in every circumstance.
For example, directors’ authority to issue shares is subject to the applicable requirements of the Companies Act, including Section 161, and the company’s constitution.
Other capital transactions may require specific shareholder approvals.
Does every share capital change require a special resolution?
No.
Different transactions have different approval requirements.
Some may involve ordinary resolutions, special resolutions, directors’ decisions or other statutory procedures.
The company should identify the requirements applicable to the particular transaction rather than assuming that every change follows the same process.
Can a sole shareholder approve a share capital change?
Potentially.
A sole shareholder may pass the required shareholder resolution where the relevant legal requirements are satisfied.
However, sole ownership does not exempt the company from the Companies Act or statutory filing obligations.
Can a company change its share capital while it has outstanding debts?
Potentially.
However, the transaction must not unlawfully prejudice creditors or breach applicable financial obligations.
A capital reduction or cash distribution requires particular attention to creditor protection and solvency.
Can a company change share capital while it is making losses?
Yes, potentially.
A company experiencing losses may raise additional equity or undertake an appropriate capital restructuring.
However, its financial circumstances must be considered, particularly where funds are proposed to be returned to shareholders.
Can a company change share capital while it is under audit?
Potentially.
The company should ensure that the transaction is properly documented and that its accounting implications are accurately reflected.
Can a company change share capital during a shareholder dispute?
Potentially, but the transaction may be challenged if it breaches legal rights or is improperly implemented.
Independent legal advice may be appropriate.
Can a company change share capital after its financial year-end but before filing its annual return?
Potentially.
The company must record the transaction in the appropriate accounting period and complete the relevant statutory filings.
Can a company reverse a completed share capital change?
Not necessarily through a simple cancellation or correction.
Once a transaction is legally effective, reversing its economic or ownership consequences may require another lawful transaction.
For example, reversing a completed share allotment is not necessarily equivalent to deleting an incorrect filing.
Can a company change share capital while preparing to strike off?
Potentially, but the purpose and consequences require careful consideration.
A company intending to close should assess outstanding liabilities, shareholder entitlements and the appropriate closure procedure.
It should not use a capital transaction to circumvent creditor protection requirements.
Can a company change share capital after it has entered liquidation?
Its ability to undertake transactions is subject to the applicable insolvency and liquidation framework.
Ordinary corporate capital transactions should not be assumed to remain available in the same way after liquidation begins.
Can a company change share capital to correct an earlier incorporation mistake?
Potentially, but the correct approach depends on the nature of the mistake.
A clerical error in a filing is different from a validly completed allotment based on an incorrect commercial assumption.
The company should establish what actually occurred before deciding how to proceed.
Common Mistakes Companies Make After Changing Share Capital
Why is it risky to confuse issued share capital with paid-up capital?
Because the two figures do not always represent the same thing.
A company may issue shares for which some subscription consideration remains unpaid.
Misstating the paid-up amount can create inaccurate corporate records and misleading financial representations.
Why is it risky to issue new shares without calculating dilution?
The allotment may unexpectedly change ownership percentages and voting influence.
Existing shareholders may lose control or important contractual protections.
Why should a company avoid treating share transfers as capital increases?
Because the company does not ordinarily receive the purchase consideration when existing shares are sold between shareholders.
A transfer changes ownership, whereas an allotment may bring new investment into the company.
Why should a company avoid using share capital to measure business valuation?
Because registered share capital and market valuation are different concepts.
A company with S$10,000 in paid-up capital may be worth substantially more or less than that amount.
Why is it important to document the source of additional capital?
Accurate documentation supports accounting records, banking due diligence, shareholder transparency and regulatory compliance.
The company should be able to explain the legal and commercial basis of the transaction.
Why should companies avoid changing capital solely to impress banks or customers?
Because increasing a registered capital figure without improving the underlying financial position may not achieve the intended commercial objective.
Banks and customers may examine actual financial performance and available resources.
Why should companies check their constitution before changing share capital?
The constitution may contain relevant provisions concerning share issues, rights, approvals and restrictions.
Ignoring these provisions can create legal disputes or defects in the transaction.
Why is it important to review shareholder agreements before issuing additional shares?
Existing shareholders may have pre-emption rights, consent requirements or anti-dilution protections.
Failing to consider these rights may lead to contractual disputes.
Why should companies avoid making capital repayments without proper procedures?
Because shareholders cannot ordinarily withdraw company capital as though it were a personal bank deposit.
An unlawful payment may create liability and require corrective action.
Why should companies not rely only on accounting entries to prove a share capital change?
Because an accounting entry does not replace the underlying legal transaction, required approvals or statutory registration.
The company’s legal and accounting records should support each other.
Decision-Making FAQs: When Should a Company Review Its Share Capital?
Should a company review its share capital when expanding into a new business?
Yes, where the expansion creates new funding requirements or regulatory obligations.
The company should assess whether its existing capital structure is suitable for the proposed activity.
Should a company review share capital before admitting an investor?
Yes.
The company should consider valuation, dilution, voting rights, investor protections and future fundraising arrangements.
Should a company review share capital before applying for bank financing?
It may be useful.
The company should understand how its existing capital, equity, debt and cash flow appear to lenders.
However, a capital increase is not automatically necessary for every financing application.
Should a company review share capital before applying for a business licence?
Yes, particularly where the intended activity is regulated.
The company should confirm whether capital, financial resource or ownership requirements apply.
Should a company review share capital when a shareholder leaves?
Yes.
The company should determine whether the exit involves a transfer, buyback, capital reduction or another arrangement.
These transactions have different consequences.
Should a company review share capital before selling the business?
Yes.
Accurate capital records and clear ownership rights can simplify due diligence and negotiations.
Should a company review share capital when it has substantial accumulated losses?
Potentially.
The company may need to evaluate its financial structure and future funding requirements.
However, an accounting or capital restructuring does not automatically solve an underlying profitability problem.
Should a company review share capital when it has surplus cash?
Potentially.
The company should first assess its operating needs, future commitments, liabilities and strategic plans.
Surplus cash does not automatically mean a capital reduction is the best option.
Should a company review share capital every year?
An annual review can be useful, especially for growing businesses or companies with multiple shareholders.
However, there is no general requirement for every company to change its share capital annually.
When is professional advice particularly important?
Professional advice is especially important where the transaction involves substantial shareholder dilution, different share classes, non-cash consideration, creditor concerns, cross-border investors, tax implications or regulated business activities.
Final FAQs: Changing Share Capital After Incorporation
Can a Singapore company start with S$1 paid-up capital and increase it later?
Yes, subject to the applicable requirements.
The initial capital amount does not necessarily determine the company’s long-term capital structure.
Can a company increase share capital without changing its UEN?
Yes.
Can a company reduce share capital without closing down?
Yes, potentially, through a lawful capital reduction.
Can a company change share capital without changing shareholders?
Yes.
Can a company change shareholders without changing share capital?
Yes, through an appropriate transfer of existing shares.
Can a company change its paid-up capital without issuing additional shares?
Yes, for example by receiving outstanding payments on existing partly paid shares.
Can a company issue additional shares without receiving cash?
Potentially, where there is valid non-cash consideration and the applicable legal requirements are satisfied.
Can a company change share capital without affecting ownership percentages?
Yes, depending on the transaction.
Can a company change share capital without affecting total equity?
Yes, certain reorganisations may change the share structure without changing total equity.
Can a company change share capital without affecting its bank balance?
Yes, depending on whether the transaction involves cash.
Can a company change share capital without affecting its business licence?
Potentially, but the relevant licensing requirements should be checked.
Can a company change share capital without affecting existing work passes?
Potentially, provided the employer continues satisfying the applicable MOM requirements.
Can a company change share capital without paying corporate income tax on the amount raised?
A genuine equity contribution is generally not ordinary taxable business income, although the specific transaction should be assessed.
Can a company change share capital without appointing new directors?
Yes.
A capital change does not automatically require a change in directors.
Can a company change share capital without changing its registered office address?
Yes.
Can a company change share capital without changing its company name?
Yes.
Can a company change share capital without changing its incorporation date?
Yes.
Does ACRA automatically approve every proposed share capital change?
No.
The company must satisfy the applicable legal requirements and complete the relevant filings or procedures.
Is a higher share capital always better for a Singapore company?
No.
An appropriate capital structure should reflect the company’s actual business needs, financial position, regulatory obligations and shareholder objectives.
What is the most important thing to remember when changing share capital after incorporation?
A share capital change is not merely a change in numbers. It may alter the company’s financial position, ownership rights, regulatory obligations and future business flexibility.
The company should understand these consequences before proceeding.
Practical Checklist: What Should a Singapore Company Do After Changing Its Share Capital?
| Area | Recommended review |
|---|---|
| Transaction classification | Confirm whether the change involves allotment, payment, reduction, subdivision, consolidation or another transaction |
| Corporate approvals | Verify the required directors’ and shareholders’ resolutions |
| Constitution | Check applicable restrictions and share rights |
| Shareholders’ agreement | Review consent, pre-emption and anti-dilution provisions |
| ACRA filings | Complete the applicable statutory filings within the required timeframe |
| Shareholder records | Verify the electronic register of members and other relevant records |
| Share certificates | Issue or replace certificates where required |
| Ownership percentages | Recalculate shareholdings and voting rights |
| Beneficial ownership | Review registrable controller information where relevant |
| Financial statements | Record the transaction using the appropriate accounting treatment |
| Banking records | Update the bank where required |
| Financing arrangements | Review financial covenants and notification obligations |
| Business licences | Confirm continued compliance with applicable conditions |
| Work pass matters | Review any relevant changes to the employer’s circumstances |
| Tax and stamp duty | Assess applicable obligations |
| Shareholder communication | Explain material ownership or rights changes |
| Supporting documents | Retain resolutions, agreements, payment evidence and filing confirmations |
| Future capital planning | Assess whether the revised structure supports the company’s long-term objectives |
Conclusion: What Really Happens When a Singapore Company Changes Its Share Capital After Incorporation?
Changing share capital after incorporation is a normal part of corporate development in Singapore.
A company may begin with modest capital and later require additional funding, new investors or a different ownership structure. It may also need to reorganise existing shares or adjust its capital to reflect changing commercial circumstances.
However, the consequences depend on the type of transaction, not simply whether the share capital figure increases or decreases.
An allotment of new shares may affect ownership percentages and voting control. Receiving payment for existing unpaid shares may increase paid-up capital without dilution. A subdivision may alter the number of shares without increasing the company’s total capital. A lawful capital reduction may affect the company’s equity and available financial resources.
The company must also consider the wider implications for ACRA records, financial reporting, banking relationships, licensing obligations, shareholder agreements and future investment opportunities.
Importantly, changing share capital does not ordinarily change the company’s legal identity, UEN, incorporation date or registered name.
For directors and shareholders, the key question should therefore be:
How will this particular share capital change affect our company’s ownership, finances, compliance obligations and future business plans?
Understanding these consequences before proceeding can help prevent unnecessary disputes, inaccurate records and avoidable compliance problems.
How ACHI BIZ Can Assist with Share Capital Changes After Incorporation
ACHI BIZ SERVICES PTE. LTD., an ACRA Licensed Corporate Service Provider (CSP), assists Singapore companies with corporate secretarial administration and statutory compliance relating to changes in share capital.
Our services may include coordinating relevant corporate resolutions, preparing share allotment and capital-related documentation, assisting with applicable ACRA Bizfile submissions, maintaining corporate records and supporting ongoing compliance.
We also help business owners understand the administrative implications of changes in their company’s ownership and capital structure.
Where a proposed transaction involves complex shareholder rights, valuation disputes, solvency assessments, significant tax consequences or other specialised legal matters, appropriate professional advice should be obtained.
Related Articles
Can a Singapore Company Return Paid-Up Capital to Its Shareholders? – FAQ Guide
Can a Singapore Pte Ltd Company Reduce Its Paid-Up Capital? – FAQ Guide
#achibiz