What Is Share Dilution in a Singapore Pte. Ltd. Company?
A Comprehensive FAQ Guide to Share Dilution, Equity Dilution Calculations, Startup Funding, Company Valuation, Founder Ownership and Financial Risks in Singapore
Share dilution is one of the most important financial considerations for business owners, startup founders, investors and shareholders of Singapore private limited companies.
When a Singapore Pte. Ltd. company issues additional shares, the ownership percentages of existing shareholders may decrease, even though those shareholders have not sold or transferred any of their shares.
This is known as share dilution, sometimes referred to as equity dilution or ownership dilution.
For example, a shareholder who originally owns 60% of a company may find that their ownership decreases to 45% following a new investment round. The shareholder continues to hold the same number of shares, but those shares now represent a smaller proportion of the company’s enlarged issued share capital.
However, dilution does not automatically mean that the shareholder has suffered a financial loss.
A company may issue additional shares to attract investment, finance expansion, develop new products, recruit key employees or acquire another business. If the transaction increases the company’s overall value, existing shareholders may benefit financially despite owning a smaller percentage.
The important distinction is between percentage ownership dilution, economic dilution and the potential impact on a shareholder’s investment value.
A shareholder may experience substantial percentage dilution while benefiting from an increase in the estimated value of their investment. Conversely, a relatively small change in ownership percentage may be financially damaging if new shares are issued at an unjustifiably low price.
Understanding these differences is particularly important for Singapore companies seeking external funding, planning multiple investment rounds or negotiating equity arrangements with business partners.
This ACHI BIZ FAQ guide examines the causes of share dilution in Singapore, practical dilution calculations, pre-money and post-money valuations, founder dilution, employee equity incentives, convertible instruments, financial risks and strategies for managing dilution.
Article focus: This guide concentrates on the financial mechanics and commercial consequences of share dilution. Detailed ACRA share allotment procedures, general shareholder rights and statutory capital restructuring processes are covered separately in other articles within the ACHI BIZ Singapore Share Capital series.
Understanding Share Dilution in Singapore Companies
What is share dilution in a Singapore Pte. Ltd. company?
Share dilution occurs when a shareholder’s percentage ownership decreases because the total number of relevant issued shares increases without that shareholder receiving a proportionate allocation of the additional shares.
Consider a Singapore company with 1,000 ordinary shares.
Shareholder A owns 600 shares, representing 60% ownership.
The company subsequently issues 500 new ordinary shares to an external investor.
The total number of issued ordinary shares increases to 1,500.
Shareholder A’s ownership becomes:
600 ÷ 1,500 × 100 = 40%
Although Shareholder A still owns 600 shares, the ownership percentage has decreased from 60% to 40%.
This represents a reduction of 20 percentage points, or a 33.33% relative reduction in the original ownership percentage.
Why does share dilution happen?
Share dilution happens because the ownership of a company is divided among a larger number of issued shares.
When additional shares are allocated to new investors or selected shareholders, the proportion represented by existing shares becomes smaller.
The company’s total issued shares increase, but the number held by non-participating shareholders remains unchanged.
Dilution therefore reflects a change in proportional ownership rather than necessarily a reduction in the actual number of shares held.
Is share dilution the same as losing shares?
No.
A shareholder can experience dilution without losing or transferring any existing shares.
For example, a shareholder may continue holding 5,000 shares before and after an investment round.
However, if the company’s total issued ordinary shares increase from 10,000 to 20,000, that shareholder’s ownership decreases from 50% to 25%.
The shareholder retains the same 5,000 shares.
What changes is the proportion those shares represent.
Is share dilution the same as a reduction in paid-up capital?
No.
Share dilution and paid-up capital reduction are different concepts.
Share dilution generally occurs when additional shares increase the total share count and change ownership percentages.
A paid-up capital reduction involves a separate corporate capital transaction and may or may not affect the number of shares or their relative ownership.
A company can experience share dilution while its paid-up capital increases.
For example, issuing new fully paid shares to an investor may increase both issued and paid-up capital while diluting existing shareholders.
Can share dilution occur without changing the company’s paid-up capital?
Certain equity-linked arrangements can create potential dilution before the actual issue of shares.
For example, granting options to subscribe for shares may affect fully diluted ownership calculations even though the options have not yet been exercised.
However, an ordinary allotment of new shares should be distinguished from a mere commitment to issue shares in the future.
The precise effect on issued capital and paid-up capital depends on the transaction and the payment terms.
Is share dilution always a disadvantage to existing shareholders?
No.
Share dilution may be commercially beneficial where the company receives valuable consideration and uses the proceeds effectively.
For example, a company valued at S$1 million before an investment may receive S$500,000 from a new investor.
Assuming the investment is made at the agreed valuation and there are no other adjustments, the post-money valuation becomes S$1.5 million.
The existing shareholders collectively own approximately 66.67% after the investment.
Their collective ownership percentage has decreased from 100% to 66.67%.
However, 66.67% of S$1.5 million is approximately S$1 million.
Their estimated investment value is unchanged immediately after the transaction under these assumptions, while the company has received additional funding.
Whether shareholders subsequently benefit depends on how successfully the company uses the investment.
Does share dilution mean the company’s value has decreased?
Not necessarily.
Share dilution measures a change in ownership percentage.
Company valuation measures the estimated economic value of the business or its equity.
These are related but distinct concepts.
A shareholder may own a smaller percentage of a more valuable company.
Alternatively, a shareholder may retain a relatively large percentage of a company whose overall value has declined.
Therefore, dilution should not be assessed without considering valuation.
Is share dilution permitted under Singapore company law?
Share dilution is not inherently unlawful.
Singapore companies may issue shares in accordance with the Companies Act 1967, their constitutions, relevant agreements and applicable corporate approval requirements.
However, a share issue may raise legal concerns if it involves improper purposes, breaches of directors’ duties, violations of contractual protections or oppressive conduct.
The legal assessment depends on the circumstances of the particular transaction.
Does every new share issue cause dilution?
No.
If all existing shareholders receive or subscribe for new shares in proportion to their existing holdings, their relative ownership percentages may remain unchanged.
For example, where two shareholders each own 50%, a proportionate issue of additional shares to both shareholders can preserve that 50:50 ownership structure.
Dilution occurs when additional shares are allocated disproportionately.
Can share dilution affect a company with only two shareholders?
Yes.
A company does not need multiple investors to experience dilution.
Suppose Shareholder A and Shareholder B each own 500 shares.
The company issues another 500 shares exclusively to Shareholder A.
The resulting ownership becomes:
-
Shareholder A: 1,000 out of 1,500 shares = 66.67%.
-
Shareholder B: 500 out of 1,500 shares = 33.33%.
Shareholder B experiences dilution even though the company has only two shareholders.
Main Causes of Share Dilution in Singapore
What are the most common causes of share dilution?
Share dilution commonly results from equity fundraising, startup investment rounds, strategic investments, employee equity incentives, conversion of equity-linked instruments and acquisition transactions involving newly issued shares.
The following table explains the principal causes.
| Cause of dilution | How dilution arises | Commercial purpose |
|---|---|---|
| External equity investment | New shares issued to investors | Raising business capital |
| Startup fundraising | Founders issue shares to venture investors | Funding growth |
| Strategic partnership | New shares issued to a business partner | Obtaining expertise, technology or market access |
| Employee share incentives | Additional shares issued to employees | Retention and performance incentives |
| Convertible loans | Outstanding debt converts into new shares | Restructuring financing |
| Convertible securities | Conversion creates additional shares | Providing flexible investment terms |
| Warrants | Holders exercise rights to subscribe for new shares | Investment incentives |
| Share-based acquisitions | Shares issued as acquisition consideration | Acquiring businesses or assets |
| Down-round financing | New shares issued at a lower valuation | Raising capital under weaker market conditions |
| Disproportionate shareholder investment | Selected shareholders subscribe for more shares | Additional capital contribution |
How does raising investment capital cause shareholder dilution?
When a Singapore company raises equity financing, it generally issues shares in exchange for investment.
The investor receives an ownership interest in the company.
Unless existing shareholders subscribe for sufficient additional shares, their percentage ownership decreases.
For example, a founder owning 100% before an investment round may retain 80% after an investor acquires 20% of the enlarged ordinary share capital.
The founder experiences 20 percentage points of dilution.
How does startup fundraising cause founder dilution?
Startup founders commonly begin with substantial or complete ownership of their companies.
As the business grows, founders may seek external investment to finance product development, recruitment, technology, marketing or international expansion.
Each funding round may involve issuing additional shares.
If founders do not receive a proportionate allocation, their ownership percentages decrease.
Multiple investment rounds can therefore produce cumulative founder dilution.
Can introducing a business partner cause dilution?
Yes.
A business partner may receive newly issued shares in exchange for funding, assets, technology or other agreed consideration.
If the company issues additional shares to that partner, existing shareholders may experience dilution.
However, if the partner acquires existing shares through a transfer from another shareholder, the transaction does not itself increase the total issued share count.
Can employee share options cause dilution?
Yes, where employees exercise options that result in newly issued shares.
An employee share option gives an eligible employee the right to acquire shares under specified conditions.
Before exercise, the options may represent potential dilution.
When exercised and new shares are issued, the company’s total issued share count increases.
The impact depends on the number of options, exercise terms and whether the shares are newly issued or transferred from existing holdings.
Can convertible loans cause share dilution?
Yes.
A convertible loan allows a lender to convert qualifying debt into shares according to agreed terms.
If conversion results in newly issued shares, existing shareholders may be diluted.
For example, a S$200,000 convertible loan may convert into equity at a negotiated valuation or conversion price.
The number of shares issued depends on the conversion mechanism.
Companies should examine these terms carefully because a conversion discount or valuation cap can increase the number of shares received by the lender.
Can preference shares cause dilution?
Yes, but the consequences depend on the rights attached to the preference shares.
Preference shares may carry different dividend, voting, redemption, conversion or liquidation rights.
A preference share issue can affect economic interests even where ordinary shareholders’ voting percentages remain unchanged.
Convertible preference shares may also create future dilution of ordinary shareholdings when conversion occurs.
Can warrants create future share dilution?
Yes.
A warrant may entitle its holder to subscribe for shares at a specified price or according to an agreed formula.
If the warrant is exercised and new shares are issued, existing shareholders may experience dilution.
Outstanding warrants are therefore relevant when assessing potential future ownership.
Does issuing bonus shares cause dilution?
A proportionate bonus issue generally does not dilute existing shareholders’ relative ownership.
For example, if every shareholder receives one bonus share for every share held, the relative ownership percentages remain unchanged.
However, special arrangements involving different share classes or non-proportionate entitlements require separate analysis.
Does a share split cause dilution?
A proportionate share split does not ordinarily cause ownership dilution.
A shareholder who owns 10% before the split generally continues owning 10% afterwards.
The number of shares increases, but the relative ownership remains unchanged.
Does transferring existing shares cause dilution?
A transfer of existing shares does not ordinarily create new-share dilution because the company’s total issued shares remain unchanged.
However, the transferring shareholder’s ownership decreases while the recipient’s ownership increases.
This is a change in ownership through a transfer, not dilution caused by an enlarged share base.
Share Dilution Calculation Formulas and Practical Examples
What is the formula for calculating share dilution?
For ordinary shares carrying equal ownership rights:
Ownership percentage = Shares held ÷ Total issued shares × 100
To calculate the change:
Dilution in percentage points = Original ownership percentage − New ownership percentage
For relative dilution:
Relative dilution percentage = (Original ownership percentage − New ownership percentage) ÷ Original ownership percentage × 100
These calculations assume the relevant shares are comparable and do not account for differences in voting or economic rights between share classes.
How do you calculate share dilution when a company issues 2,000 new shares?
Assume a company initially has 8,000 ordinary shares.
Shareholder A owns 4,800 shares.
Shareholder B owns 3,200 shares.
The company issues 2,000 new shares to Investor C.
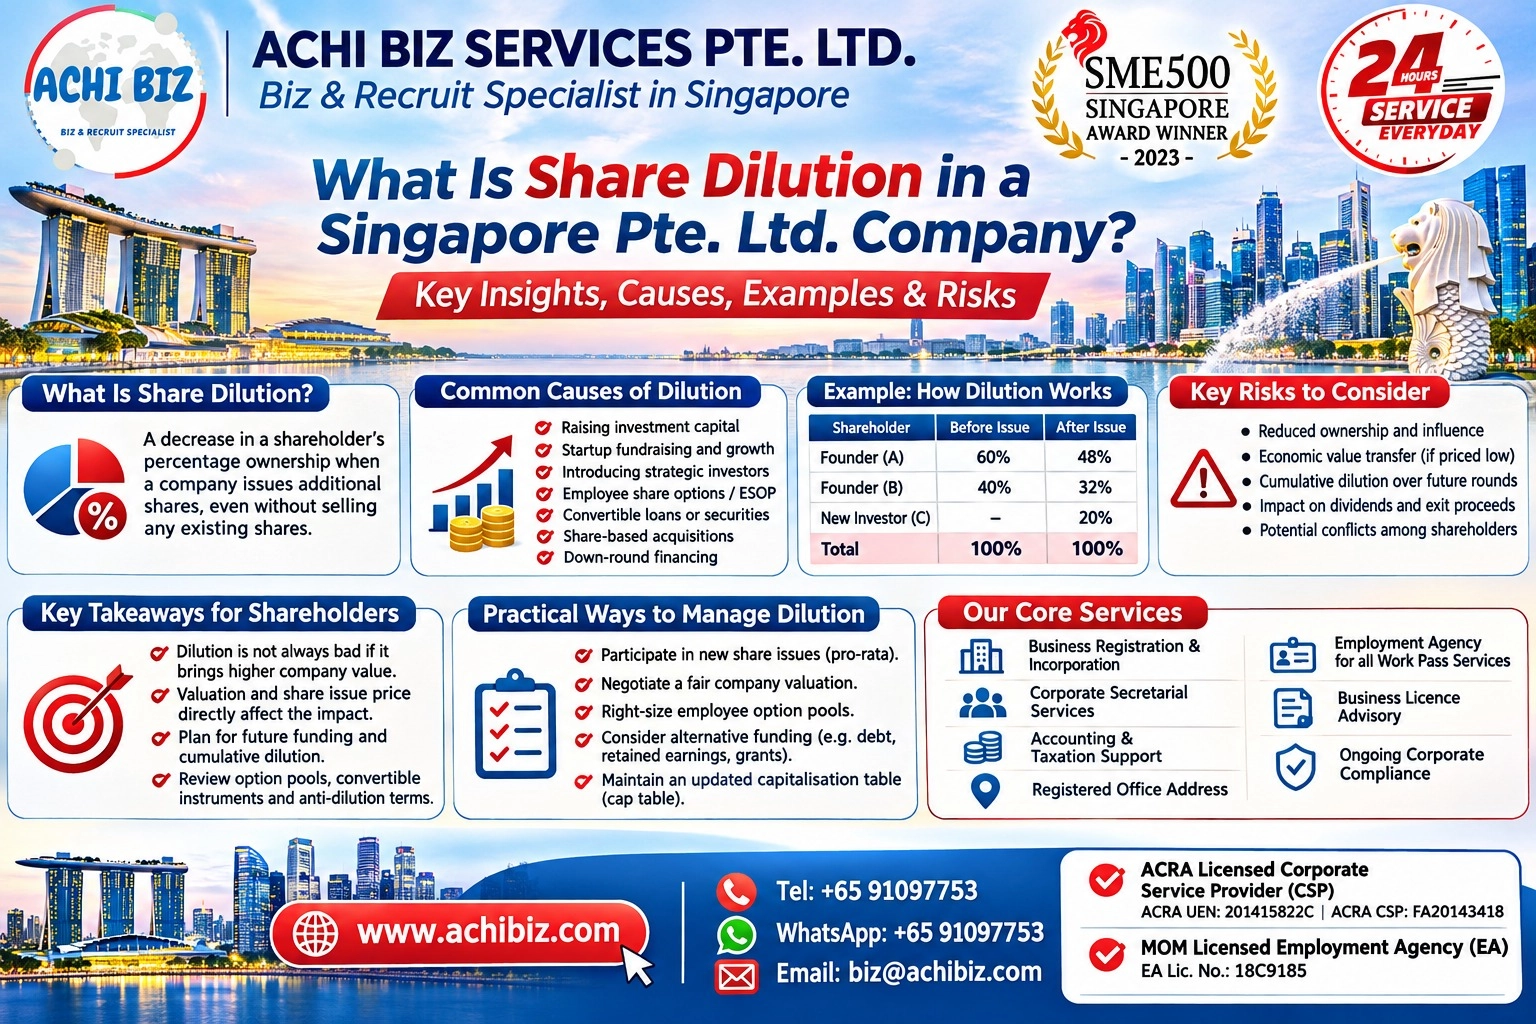
| Shareholder | Before issue | Before ownership | After issue | After ownership |
|---|---|---|---|---|
| A | 4,800 | 60% | 4,800 | 48% |
| B | 3,200 | 40% | 3,200 | 32% |
| C | 0 | 0% | 2,000 | 20% |
| Total | 8,000 | 100% | 10,000 | 100% |
Shareholder A’s ownership decreases from 60% to 48%.
Shareholder B’s ownership decreases from 40% to 32%.
Investor C acquires 20%.
What is the difference between percentage-point dilution and relative dilution?
Suppose a shareholder’s ownership decreases from 50% to 40%.
The reduction is 10 percentage points.
However, the relative reduction in the shareholder’s original ownership is:
(50 − 40) ÷ 50 × 100 = 20%
Therefore, the shareholder has experienced a 10-percentage-point reduction, equivalent to 20% relative dilution.
These measurements should not be confused.
How can a shareholder calculate dilution without knowing the share issue price?
Basic ownership dilution can be calculated from the relevant share counts.
The subscription price is not necessary to determine the percentage ownership before and after an allotment.
However, the issue price is essential when evaluating economic dilution, investment value and whether the company has received appropriate consideration.
How many new shares must be issued for an investor to own 20%?
Assume a company has 10,000 existing ordinary shares.
The investor must receive 2,500 new shares to own 20% of the enlarged issued ordinary shares.
Calculation:
2,500 ÷ 12,500 × 100 = 20%
The existing shareholders collectively retain 80%.
How many new shares must be issued for an investor to own 25%?
Assume a company has 12,000 existing ordinary shares.
The investor must receive 4,000 new shares.
The enlarged share count becomes 16,000.
4,000 ÷ 16,000 × 100 = 25%
Existing shareholders collectively retain 75%.
Can a shareholder calculate dilution from paid-up capital alone?
No, not reliably.
The monetary amount of paid-up capital does not necessarily correspond directly to the proportion of shares held.
Companies may issue shares at different prices and have different share classes.
Dilution calculations should use the relevant issued share counts and rights rather than relying solely on monetary paid-up capital.
Can a shareholder be diluted by 50% without losing any shares?
Yes.
Suppose a shareholder owns 5,000 out of 10,000 ordinary shares, representing 50%.
The company subsequently issues another 10,000 ordinary shares to other investors.
The shareholder continues holding 5,000 shares, but the total becomes 20,000.
Ownership falls to 25%.
The shareholder has experienced a 50% relative reduction in the original ownership percentage.
How can a company calculate the number of new shares required for a target investor ownership percentage?
For a straightforward new issue of equal-rights ordinary shares:
New shares required = Existing shares × Target investor ownership percentage ÷ (100% − Target investor ownership percentage)
For example, where a company has 15,000 shares and wishes to issue a new investor 25% of the enlarged capital:
15,000 × 25% ÷ 75% = 5,000 new shares
The resulting total is 20,000 shares.
The investor owns 25%.
Where the calculation produces fractional shares, the company must consider an appropriate whole-share structure and any applicable rounding or restructuring requirements.
Pre-Money and Post-Money Valuation in Share Dilution
What is pre-money valuation in Singapore startup fundraising?
Pre-money valuation is the agreed equity valuation of a company immediately before a new investment is added.
For example, if a Singapore startup has a negotiated pre-money valuation of S$2 million, that represents the agreed value of its existing equity before the proposed investment.
The valuation may be based on revenue, profitability, assets, growth potential, technology, comparable transactions or investor negotiations.
It is not necessarily the same as the company’s paid-up capital or accounting net assets.
What is post-money valuation?
Post-money valuation is the company’s agreed equity valuation immediately after the investment.
For a straightforward cash equity investment:
Post-money valuation = Pre-money valuation + New investment
For example:
Pre-money valuation: S$2 million
New investment: S$500,000
Post-money valuation: S$2.5 million
This simplified formula assumes no additional adjustments, option-pool changes or other transaction-specific valuation terms.
How does pre-money valuation affect share dilution?
A higher pre-money valuation generally allows a company to raise a fixed amount of equity investment while issuing a smaller percentage of its enlarged share capital.
For example:
| Scenario | Pre-money valuation | Investment | Post-money valuation | New investor ownership |
|---|---|---|---|---|
| A | S$1,000,000 | S$500,000 | S$1,500,000 | 33.33% |
| B | S$2,000,000 | S$500,000 | S$2,500,000 | 20% |
| C | S$4,000,000 | S$500,000 | S$4,500,000 | 11.11% |
The same S$500,000 investment produces different ownership outcomes depending on the agreed valuation.
Why does a lower company valuation result in greater dilution?
A lower valuation means investors generally receive a larger proportion of the company’s equity for the same investment amount.
For example, a S$500,000 investment represents one-third of a company valued at S$1.5 million after investment.
However, it represents only 20% of a company valued at S$2.5 million after investment.
Therefore, the valuation negotiated during fundraising directly affects the dilution experienced by existing shareholders.
Does a company’s paid-up capital determine its pre-money valuation?
No.
Paid-up capital records capital contributed or credited as paid on issued shares.
Pre-money valuation reflects the negotiated economic value of the company’s equity.
A Singapore company with S$10,000 paid-up capital may be valued at several million dollars if it has valuable technology, profitable operations or strong growth prospects.
Conversely, a company with substantial paid-up capital may have a lower valuation if it has suffered significant losses.
Can a company issue shares above its previous subscription price?
Yes.
Singapore companies may issue shares at different subscription prices, subject to applicable law, their constitutions and relevant approvals.
A company that originally issued shares at S$1 each may subsequently issue shares at a substantially higher price if commercially justified.
The resulting dilution depends on the number of new shares issued, not simply the increase in the subscription price.
Does issuing shares at a higher price reduce dilution?
For a fixed investment amount, a higher price per share generally means fewer new shares are issued.
This normally reduces percentage dilution, assuming comparable share rights and no other adjustments.
For example:
| Investment amount | Subscription price per share | New shares issued |
|---|---|---|
| S$100,000 | S$1 | 100,000 |
| S$100,000 | S$2 | 50,000 |
| S$100,000 | S$5 | 20,000 |
A higher subscription price produces fewer new shares for the same investment.
However, the price must be assessed against the company’s actual commercial circumstances.
Can a high company valuation create future dilution risks?
Yes.
An excessively optimistic valuation may create difficulties during subsequent fundraising.
If the company fails to achieve its expected growth, future investors may demand a lower valuation.
This can lead to a down round, potentially resulting in greater dilution and the activation of contractual anti-dilution provisions.
Is the highest possible valuation always best for existing shareholders?
Not necessarily.
A high valuation may minimise immediate dilution, but it can also create unrealistic investor expectations.
Companies should consider whether the valuation is sustainable, commercially defensible and compatible with future funding requirements.
A reasonable valuation combined with a suitable long-term investor may be more beneficial than an inflated valuation that creates problems during subsequent financing rounds.
Economic Dilution Versus Ownership Percentage Dilution
What is economic dilution?
Economic dilution concerns the effect of a transaction on the value attributable to existing shareholders.
It differs from percentage dilution, which measures the change in proportional ownership.
For example, a shareholder may own 50% of a company valued at S$1 million.
The estimated value of that interest is S$500,000.
Following an investment, the shareholder may own only 40% of a company valued at S$1.5 million.
The estimated value of the interest becomes S$600,000.
Although ownership has decreased, the estimated investment value has increased.
This example assumes the valuation figures are reasonable and that the shares carry comparable economic rights.
Can shareholders experience dilution without losing investment value?
Yes.
A shareholder can experience percentage dilution without suffering an immediate reduction in estimated investment value.
For example:
| Item | Before investment | After investment |
|---|---|---|
| Company equity valuation | S$1,000,000 | S$1,500,000 |
| Shareholder ownership | 60% | 40% |
| Estimated value of shareholding | S$600,000 | S$600,000 |
The shareholder’s ownership percentage falls by 20 percentage points.
However, the estimated value of the holding remains S$600,000.
The actual economic outcome may differ because private company valuations are estimates rather than guaranteed realisable values.
Can share dilution increase the value of an existing shareholder’s investment?
Yes.
Suppose a shareholder owns 50% of a company valued at S$2 million.
The estimated value of the holding is S$1 million.
After a successful investment and business expansion, the company is valued at S$5 million.
The shareholder now owns 35%.
The estimated value of the holding is:
35% × S$5 million = S$1.75 million
Despite dilution from 50% to 35%, the estimated investment value has increased by S$750,000.
However, this increase depends on the later valuation and does not represent a guaranteed financial return.
Can shareholders suffer economic dilution even when the company receives new investment?
Yes.
Economic dilution may arise if new shares are issued at a price that transfers disproportionate value to new investors.
For example, suppose a company has an equity value of S$1 million and 100,000 ordinary shares.
The implied value per share is S$10.
If the company issues 100,000 additional shares for only S$100,000, the simplified post-investment equity value becomes S$1.1 million.
There are now 200,000 shares.
The implied value per share becomes S$5.50.
Existing shareholders collectively own 50%, with an estimated value of S$550,000.
Under these assumptions, their collective economic interest has decreased from S$1 million to S$550,000.
This illustrates why the subscription price can be as important as the ownership percentage.
What is the difference between ownership dilution and value dilution?
Ownership dilution measures how much a shareholder’s percentage interest decreases.
Value dilution considers whether the economic value attributable to the shareholder has decreased.
The two may occur together, but they are not identical.
A shareholder should examine both before deciding whether a proposed equity investment is financially reasonable.
Can a shareholder suffer financial loss without any share dilution?
Yes.
A company’s value may decrease because of operating losses, declining revenue, increased liabilities, business competition or other commercial risks.
A shareholder may retain exactly the same ownership percentage while the estimated value of the investment declines.
Therefore, not every investment loss is caused by dilution.
Does share dilution automatically reduce dividends?
No.
Dilution may reduce a shareholder’s proportion of distributions where the relevant shares carry equal dividend rights.
However, the actual dividend received depends on the company’s profits, available distributable reserves, dividend policy and rights attached to the shares.
If new investment substantially increases profitability, the total dividend available for distribution may also increase.
Can dilution affect a shareholder’s proceeds when the company is sold?
Yes.
A shareholder’s ownership percentage may affect the proportion of sale proceeds attributable to that shareholder.
However, the actual amount received also depends on the sale price, liabilities, transaction costs, preference rights and contractual distribution arrangements.
A smaller ownership percentage in a more valuable company may produce higher proceeds than a larger percentage in a less valuable company.
Founder Dilution in Singapore Startups
What is founder dilution?
Founder dilution occurs when the percentage ownership held by a company’s founders decreases as additional equity is issued.
This commonly happens when startups raise external investment or establish equity incentive arrangements.
Founder dilution is a normal feature of many growth-oriented businesses, but it should be planned carefully.
How much equity do startup founders typically lose during fundraising?
There is no universal percentage.
The dilution depends on the company’s valuation, funding requirements, investor negotiations, stage of development and existing capital structure.
For example, an investor acquiring 15% of a company’s enlarged equity will generally cause existing non-participating shareholders to retain 85% of their previous proportional ownership.
A later financing round may produce further dilution.
The appropriate percentage depends on the company’s circumstances rather than a fixed Singapore regulatory benchmark.
How does dilution accumulate over multiple investment rounds?
Consider a founder who initially owns 100% of a Singapore startup.
The company completes three financing rounds, with new investors acquiring 20%, 15% and 10% of the enlarged equity in successive rounds.
Assuming the founder does not participate and there are no other changes:
| Stage | Founder ownership |
|---|---|
| Before investment | 100% |
| After Round 1: 20% new investor ownership | 80% |
| After Round 2: 15% new investor ownership | 68% |
| After Round 3: 10% new investor ownership | 61.2% |
The founder retains 61.2% after the three rounds.
This illustrates cumulative dilution.
The percentages should not simply be subtracted from the original 100%, because each new round applies to the ownership structure existing immediately before that round.
Can founders lose majority ownership through repeated dilution?
Yes.
A founder may begin with majority ownership but eventually hold less than 50% following successive financing rounds.
However, ownership percentage alone does not determine every aspect of corporate control.
Voting rights, shareholder agreements, board arrangements and reserved matters may also be relevant.
Is losing majority ownership always bad for a founder?
Not necessarily.
A founder may retain a smaller ownership percentage while benefiting from a substantially more valuable company.
External investors may also contribute experience, commercial relationships and financial resources.
Nevertheless, founders should consider the consequences of reduced voting influence, changes in board composition and future financing requirements.
Should founders calculate future dilution before accepting their first investor?
Yes.
Founders should consider not only the immediate investment but also the likely capital requirements of the business over the next several years.
A company that expects multiple fundraising rounds should assess how future investment, employee equity incentives and convertible instruments may affect founder ownership.
Can founders experience dilution even when they remain employed as directors?
Yes.
A founder’s position as a director or employee is separate from the founder’s percentage ownership.
Continuing to manage the company does not automatically prevent dilution.
Can a founder own less than 50% and still manage the company?
Yes.
Management responsibility and ownership percentage are not necessarily identical.
A founder may continue serving as a director or chief executive even after becoming a minority shareholder.
However, the founder’s authority depends on the company’s governance arrangements, board decisions and applicable agreements.
Can founders prevent all future dilution?
They may negotiate contractual protections, but complete protection from dilution is not always commercially realistic.
Future investors may require equity participation, and companies may need additional funding.
Founders should consider the cost of preserving ownership against the potential benefits of raising capital.
Employee Share Options and Equity Incentive Dilution
What is an employee share option pool?
An employee share option pool is an allocation or reserve of equity-related rights intended for eligible employees, directors or other participants.
The pool may be used to incentivise performance, reward contributions or encourage long-term retention.
The structure may involve options over newly issued shares or other arrangements.
Does creating an employee option pool immediately dilute existing shareholders?
Not necessarily on an issued-share basis.
If the company merely reserves shares for potential future issuance, its existing issued share count may remain unchanged.
However, the reserved options may be included in fully diluted ownership calculations.
The effect depends on the legal structure of the arrangement.
What is option pool dilution?
Option pool dilution refers to the potential or actual reduction in existing shareholders’ proportional ownership arising from shares allocated under an employee option arrangement.
For example, a company may establish an option pool representing 10% of its fully diluted equity.
The actual impact depends on whether the pool is created before or after an investment, how the calculation is defined and whether the options are ultimately exercised.
Why do investors sometimes require an employee option pool before investing?
Investors may want the company to retain sufficient equity incentives to attract and retain key employees.
A pre-investment option pool increase may cause more of the dilution burden to fall on existing shareholders rather than the incoming investor.
This is why the timing and calculation of an option pool can materially affect investment negotiations.
What is the difference between a pre-money option pool and a post-money option pool?
A pre-money option pool adjustment is generally incorporated into the capitalisation structure before calculating the incoming investor’s ownership.
A post-money arrangement is implemented after the investment or otherwise structured so that dilution is allocated differently.
The precise economic effect depends on the transaction documents.
Companies should request a fully diluted capitalisation table showing the effect of the option pool under each proposed structure.
Can employee options create dilution even if employees never exercise them?
Unexercised options may appear in fully diluted calculations, but they do not necessarily create actual issued-share dilution.
If the options expire without exercise, the anticipated dilution may never occur.
Should Singapore startups reserve shares for future employees?
This may be commercially appropriate where employee equity incentives form part of the company’s recruitment and retention strategy.
However, the size of the pool should reflect realistic staffing needs, the company’s growth plans and investor expectations.
An unnecessarily large pool may create avoidable potential dilution.
Convertible Instruments and Hidden Dilution Risks
What is a convertible note in startup fundraising?
A convertible note is a financing instrument under which an investor provides funds that may convert into equity according to agreed conditions.
Conversion may occur during a future financing round or another specified event.
The terms can include interest, maturity provisions, valuation caps and conversion discounts.
How does a convertible note cause dilution?
When the note converts into newly issued shares, the total share count increases.
The number of conversion shares depends on the agreed conversion formula.
A lower conversion price generally results in more shares being issued for the same convertible amount.
This can increase dilution for existing shareholders.
What is a valuation cap in a convertible note?
A valuation cap is a contractual mechanism that may limit the valuation used to determine the conversion price.
For example, an investor may agree to convert a loan using a valuation cap lower than the valuation achieved in the next financing round.
This can allow the investor to receive shares at a more favourable conversion price.
The exact outcome depends on the agreement.
How does a conversion discount affect dilution?
A conversion discount allows an investor to convert at a lower price than the price paid by certain new investors, subject to the agreed terms.
For example, a 20% discount to a S$2 share price would produce a conversion price of S$1.60.
A S$160,000 convertible amount would therefore convert into 100,000 shares at that price, ignoring interest and other adjustments.
Without the discount, the same amount at S$2 per share would produce 80,000 shares.
The discounted conversion results in more shares and potentially greater dilution.
Can convertible loans cause unexpected dilution?
Yes.
Shareholders may underestimate the number of shares that will be issued when a convertible instrument is eventually converted.
The risk is greater where the conversion terms include discounts, valuation caps, accrued interest or adjustments linked to future fundraising.
What is a SAFE agreement, and can it cause dilution?
A SAFE, commonly described as a Simple Agreement for Future Equity, is an investment arrangement intended to provide rights to future equity under specified conditions.
Its legal and commercial treatment depends on the particular agreement and applicable law.
Where a SAFE results in newly issued shares, existing shareholders may experience dilution.
Singapore companies considering SAFEs should obtain appropriate legal and financial advice rather than assuming that standard overseas templates automatically suit their circumstances.
Can multiple convertible instruments make dilution difficult to calculate?
Yes.
A company may have several convertible loans, SAFEs, warrants and employee options outstanding.
Each instrument may contain different conversion prices, valuation caps or adjustment mechanisms.
The final ownership structure can therefore be significantly more complicated than a straightforward cash share issue.
A fully diluted capitalisation table is particularly useful in these situations.
Fully Diluted Share Capital and Capitalisation Tables
What is fully diluted ownership?
Fully diluted ownership is a calculation of potential ownership assuming specified equity-linked instruments are converted or exercised into shares.
It may include outstanding options, warrants, convertible instruments and other rights to receive shares.
However, there is no single universal calculation that applies to every transaction.
The company must define which instruments and assumptions are included.
What is the difference between issued-share ownership and fully diluted ownership?
Issued-share ownership is calculated using shares already issued.
Fully diluted ownership considers additional shares that may be issued under specified assumptions.
For example:
A company has 100,000 issued ordinary shares.
A shareholder owns 40,000 shares.
The shareholder’s current issued-share ownership is 40%.
The company also has options and convertible instruments representing 25,000 additional ordinary shares under the chosen fully diluted assumptions.
The shareholder’s fully diluted ownership becomes:
40,000 ÷ 125,000 × 100 = 32%
The shareholder therefore has 40% current ownership but 32% fully diluted ownership under those assumptions.
What is a capitalisation table?
A capitalisation table, often called a cap table, records the ownership structure of a company.
It typically shows shareholders, share classes, issued shares, ownership percentages and relevant equity-linked instruments.
A well-maintained cap table helps companies evaluate current ownership and model future dilution.
Why is a cap table important for Singapore startups?
A cap table helps founders and investors understand how different fundraising scenarios affect ownership.
It can identify potential dilution from employee options, convertible notes and future investment rounds.
It also supports investment negotiations, valuation analysis and financial planning.
What information should a dilution cap table contain?
A useful dilution cap table should identify:
-
Existing shareholders and their shareholdings.
-
Relevant share classes and rights.
-
Total issued shares.
-
Outstanding options, warrants and convertible instruments.
-
Proposed new investment and subscription terms.
-
Pre-money and post-money valuations.
-
Ownership percentages before and after financing.
-
Fully diluted ownership under clearly stated assumptions.
-
Potential future fundraising scenarios.
Can a cap table replace a company’s statutory register of members?
No.
A cap table is a financial and ownership modelling tool.
It does not replace the statutory register of members or applicable ACRA records.
The company’s legal ownership records and financial models should be consistent, but they serve different purposes.
Should a company update its cap table after every investment round?
Yes.
Updating the cap table helps management and shareholders understand the company’s current and potential future ownership structure.
It also reduces the risk of relying on outdated dilution calculations during negotiations.
Down-Round Financing and Share Dilution Risks
What is a down round?
A down round occurs when a company raises equity financing at a lower valuation than an earlier financing round, using the relevant comparable valuation basis.
Down rounds may arise because of weaker financial performance, market conditions, reduced investor confidence or urgent funding requirements.
Why can a down round create significant dilution?
A lower valuation generally means investors receive a larger ownership percentage for a fixed investment amount.
Consequently, existing shareholders may experience greater dilution than they would have at the earlier valuation.
Can a down round reduce the value of existing shareholders’ investments?
Yes.
A lower valuation may indicate that the estimated economic value of the company has decreased.
Existing shareholders may therefore experience both a decline in estimated investment value and additional percentage dilution.
What is anti-dilution protection?
Anti-dilution protection refers to contractual mechanisms designed to protect specified investors against certain forms of dilution, particularly where later financing occurs at a lower price.
These provisions may adjust conversion prices or provide other contractual remedies.
They do not necessarily prevent all dilution.
What is a full-ratchet anti-dilution provision?
A full-ratchet provision may adjust an investor’s applicable conversion price to the lower price used in a subsequent qualifying financing round.
This can significantly increase the number of shares the protected investor receives upon conversion.
The resulting dilution may fall disproportionately on other shareholders.
What is weighted-average anti-dilution protection?
Weighted-average anti-dilution provisions generally adjust the relevant conversion price using a formula that considers factors such as the number of shares issued and the price of the new financing.
The adjustment is often less severe than a full-ratchet mechanism, although the outcome depends on the formula.
Which anti-dilution mechanism is more favourable to founders?
From a founder’s perspective, weighted-average protection is often less dilutive than full-ratchet protection in a down round.
However, the commercial impact depends on the transaction terms, share classes and future financing scenarios.
Can anti-dilution protection create unequal outcomes among shareholders?
Yes.
Investors holding protected securities may receive favourable adjustments that are not available to ordinary shareholders.
This can result in unequal economic consequences when the company raises additional capital at a lower valuation.
Should founders accept anti-dilution clauses without modelling their effects?
No.
Founders should understand how the clauses operate under different financing scenarios.
A provision that appears commercially acceptable during an initial investment may create substantial dilution in a later down round.
Financial and Commercial Risks of Share Dilution
What are the main financial risks of share dilution?
The principal risks include reduced ownership percentages, potential economic value transfer, lower participation in future distributions, exposure to unfavourable investment pricing and cumulative dilution across multiple financing rounds.
The severity of these risks depends on the company’s valuation and transaction terms.
Can excessive dilution discourage startup founders?
Yes.
If founders experience substantial dilution during early fundraising, their remaining economic interest may become less attractive.
This can affect motivation, future investment negotiations and long-term ownership planning.
However, the appropriate founder ownership level depends on the company’s circumstances and incentive arrangements.
Can excessive dilution make future fundraising more difficult?
Potentially.
Future investors may examine whether founders and key employees retain sufficient economic incentives to continue developing the business.
A complicated capitalisation table or heavily diluted founding team may create additional negotiation challenges.
Can dilution affect the value of minority shareholdings?
Yes.
A minority shareholder’s economic interest may be affected by dilution, particularly where the company issues shares at an unfavourable valuation.
Minority shareholdings may also be difficult to sell because private company shares are generally less liquid than publicly traded securities.
The combination of dilution and limited liquidity can create financial risk.
Can dilution create disagreements between business partners?
Yes.
Disagreements may arise where shareholders have different expectations about investment needs, company valuation or the allocation of new shares.
For example, one shareholder may favour raising additional capital while another may prefer retaining the existing ownership structure.
Clear financial projections and transparent communication can help reduce misunderstandings.
Can dilution affect succession planning in a family-owned company?
Yes.
A family-owned Singapore company may experience dilution when external investors or selected family members receive additional shares.
This can change the economic interests of family shareholders and affect long-term ownership planning.
Such transactions should be considered carefully where preserving family ownership is a commercial priority.
Can share dilution affect the proceeds from a future business sale?
Yes.
If a company is sold, shareholders’ proceeds generally depend on their economic rights and the applicable transaction arrangements.
Dilution may reduce the proportion of sale proceeds attributable to an existing shareholder.
However, a successful investment strategy may increase the overall sale value sufficiently to offset the lower ownership percentage.
Can dilution increase a shareholder’s financial exposure?
Dilution itself does not ordinarily create a new personal liability merely because the shareholder’s percentage ownership decreases.
However, shareholders may choose to invest additional funds to maintain their ownership.
This can increase the amount of capital they have committed to the business.
Any separate guarantees, contractual commitments or unpaid share obligations must also be considered.
Can dilution affect a shareholder’s ability to exit the company?
Potentially.
A smaller shareholding may have different commercial attractiveness to prospective purchasers.
The shareholder’s ability to sell may also depend on transfer restrictions, shareholders’ agreements and market demand.
Dilution does not automatically remove the shareholder’s ability to transfer shares, but it may affect the economics of an exit.
Managing and Minimising Share Dilution
Can shareholders avoid dilution by participating in new investment rounds?
Potentially.
A shareholder may preserve their proportional ownership by subscribing for an appropriate proportion of newly issued shares.
However, participation depends on the terms of the investment, applicable rights and the shareholder’s financial capacity.
What is pro-rata investment participation?
Pro-rata participation generally refers to an investor’s opportunity to subscribe for additional shares in proportion to an existing ownership interest.
For example, a shareholder owning 20% may seek to subscribe for 20% of a new issue to maintain that percentage.
The exact rights and calculations depend on the relevant agreements and transaction structure.
Can a shareholder maintain ownership without investing additional money?
Sometimes, depending on the transaction.
For example, a proportionate bonus issue may preserve ownership percentages without requiring additional cash subscriptions.
However, where a company raises new equity from external investors, a non-participating shareholder will generally experience dilution unless another arrangement preserves their interest.
Can companies reduce dilution by raising less equity capital?
Yes.
A smaller equity investment generally requires issuing a smaller ownership percentage at the same valuation.
However, raising insufficient capital may expose the business to funding shortages.
Companies should balance dilution concerns against realistic operating and growth requirements.
Can debt financing help avoid share dilution?
Debt financing can provide funding without immediately issuing additional shares.
However, borrowing introduces repayment obligations, interest expenses and potentially security requirements.
Convertible debt may also create future dilution.
Therefore, debt financing should not be considered automatically superior to equity financing.
Can retained earnings help companies avoid dilution?
Yes.
A profitable company may use retained earnings to finance business expansion without issuing additional shares.
However, this depends on the company’s available financial resources and operational requirements.
Retained earnings do not necessarily represent cash available for immediate use.
Can shareholders negotiate a higher valuation to reduce dilution?
Yes.
A higher negotiated valuation generally reduces the ownership percentage required for a fixed investment amount.
However, the valuation should be commercially defensible.
An unrealistic valuation may create problems during later fundraising.
Can companies use staged investment to manage dilution?
Potentially.
Investment may be structured in stages linked to agreed milestones.
This can allow a company to obtain initial funding while deferring some future equity issuance.
However, staged financing introduces additional conditions and uncertainty.
The overall economic effect depends on the agreed terms.
Can companies use non-equity funding to minimise dilution?
Yes.
Depending on eligibility and commercial circumstances, companies may consider bank financing, shareholder loans, retained earnings, grants or other non-equity funding arrangements.
Each alternative has different costs, restrictions and risks.
Should companies prioritise minimising dilution over obtaining investment?
Not necessarily.
Minimising dilution should not be the only objective.
A company may benefit from accepting reasonable dilution if the investment provides capital, expertise or commercial opportunities that substantially increase its long-term value.
The more useful question is whether the company is receiving sufficient economic and strategic value for the ownership interest issued.
Share Dilution and Minority Shareholder Financial Interests
Why is share dilution particularly important for minority shareholders?
Minority shareholders may have limited ability to influence fundraising decisions.
If new shares are issued disproportionately, their ownership percentages may decrease further.
This can affect their economic participation and, depending on the circumstances, their practical influence within the company.
Can a minority shareholder experience substantial dilution in a single transaction?
Yes.
For example, a minority shareholder owning 20% of a company may see that interest fall to 10% if the total issued shares double and the shareholder receives no additional shares.
The shareholder retains the same number of shares but owns half the previous percentage.
Can dilution be used to disadvantage a minority shareholder?
A share issue may be challenged where the circumstances support a recognised legal claim, such as improper conduct or oppression.
However, dilution alone does not establish wrongdoing.
The company’s commercial purpose, directors’ conduct, applicable rights and transaction terms are relevant.
Is an unfairly low share issue price a warning sign?
Yes.
A subscription price substantially below a reasonable company valuation may warrant closer examination, particularly where the new shares are issued to connected parties.
However, a low price is not automatically improper.
The company’s financial condition, funding urgency, commercial negotiations and other relevant circumstances must be considered.
Can shareholders request an independent valuation before a dilutive transaction?
An independent valuation may be commercially appropriate, particularly where the proposed transaction is substantial or the pricing is disputed.
Whether shareholders are legally entitled to require one depends on the circumstances and applicable rights.
Can shareholders negotiate contractual protection against dilution?
Yes.
Shareholders may negotiate appropriate provisions concerning future financing, participation rights, valuation adjustments and other investor protections.
The legal effect depends on the wording and enforceability of the arrangements.
Detailed legal treatment of pre-emption rights and shareholder protections is addressed separately within the ACHI BIZ share capital article series.
What should a minority shareholder examine before accepting dilution?
A minority shareholder should assess the company’s funding requirements, proposed valuation, subscription price, expected commercial benefits, resulting ownership percentage and potential future financing needs.
The shareholder should also consider the company’s financial position and whether the transaction creates disproportionate economic benefits for particular parties.
Share Dilution in Foreign-Owned Singapore Companies
Can a foreign-owned Singapore Pte. Ltd. company experience share dilution?
Yes.
Share dilution applies regardless of whether the shareholders are Singapore residents, foreign individuals or overseas corporate entities.
A foreign-owned company may experience dilution when it issues additional shares to new or existing investors.
Can a foreign parent company be diluted in its Singapore subsidiary?
Yes.
For example, a foreign parent company may initially own 100% of a Singapore subsidiary.
If the subsidiary issues shares to an external investor, the parent’s ownership percentage may decrease.
The parent company should assess the commercial and governance consequences before proceeding.
Can a foreign investor acquire a minority interest through a dilutive share issue?
Yes, subject to applicable laws, regulatory requirements and any industry-specific restrictions.
The Singapore company may issue shares to a foreign investor, resulting in dilution of existing shareholders.
However, certain regulated activities or business sectors may involve additional ownership or licensing considerations.
Does share dilution automatically affect a company’s Singapore incorporation status?
No.
A change in ownership percentage does not ordinarily change the company’s legal identity or incorporation status.
However, changes in ownership may have consequences under particular licences, contracts or regulatory frameworks.
Can dilution affect a company’s ultimate beneficial ownership structure?
Yes.
New share issues may change the persons or entities holding ownership interests in the company.
Depending on the circumstances, this may affect beneficial ownership assessments and applicable corporate recordkeeping obligations.
Companies should review their relevant statutory registers and compliance requirements when ownership changes.
Share Dilution and Investment Exit Planning
Why should investors consider future dilution before investing?
An investor’s initial ownership percentage may not remain unchanged.
Future fundraising, employee share incentives and convertible instruments may reduce that percentage.
Investors should therefore assess both current ownership and potential fully diluted ownership.
Can an investor initially owning 20% eventually own less than 10%?
Yes.
If the company completes multiple financing rounds and the investor does not participate proportionately, the ownership percentage may fall below 10%.
The exact result depends on the size and structure of each round.
Does a smaller ownership percentage always mean lower exit proceeds?
No.
A smaller percentage of a significantly more valuable company may produce higher proceeds.
For example:
| Scenario | Ownership | Company sale value | Simplified shareholder proceeds |
|---|---|---|---|
| Before growth | 30% | S$2 million | S$600,000 |
| After dilution and growth | 15% | S$8 million | S$1.2 million |
The shareholder’s ownership decreases by half, but the simplified proceeds double.
This example assumes equal economic rights and excludes liabilities, liquidation preferences, transaction costs and other adjustments.
Can liquidation preferences change the economic effect of dilution?
Yes.
Some investors may hold preference shares with contractual rights to receive specified amounts before ordinary shareholders participate in remaining distributions.
In such cases, the percentage ownership shown in a cap table may not accurately represent the amount each shareholder receives upon a sale or liquidation event.
The relevant share rights and investment agreements must be examined.
Why is a shareholder’s percentage ownership not always equal to the percentage of sale proceeds received?
Different share classes may carry different economic rights.
Investors may also have preferential distribution entitlements or other contractual arrangements.
Therefore, a shareholder owning 20% of the issued shares does not necessarily receive exactly 20% of the total transaction proceeds.
Can share dilution affect the attractiveness of a company to potential buyers?
Potentially.
Buyers may examine the company’s capital structure, outstanding options, convertible instruments and shareholder arrangements.
A complicated ownership structure may increase transaction complexity.
Clear and accurate equity records can support due diligence and negotiations.
Practical Share Dilution Examples for Singapore Companies
The following hypothetical examples illustrate different dilution scenarios. They are simplified for educational purposes and assume ordinary shares with equal rights unless otherwise stated.
How does dilution affect a sole founder bringing in the first investor?
A founder owns all 10,000 shares in a Singapore company.
The company issues 2,500 shares to an investor.
After the allotment:
-
Founder: 10,000 shares, representing 80%.
-
Investor: 2,500 shares, representing 20%.
The founder experiences 20 percentage points of dilution.
The financial outcome depends on the investment received and the company’s resulting value.
How does dilution affect two equal business partners?
Two shareholders each own 5,000 shares in a company with 10,000 issued shares.
The company issues 5,000 new shares to a third investor.
| Shareholder | Before | After |
|---|---|---|
| Partner A | 50% | 33.33% |
| Partner B | 50% | 33.33% |
| New investor | 0% | 33.33% |
Each original shareholder experiences approximately 16.67 percentage points of dilution.
What happens when only one existing shareholder subscribes for additional shares?
Shareholder A owns 60,000 shares.
Shareholder B owns 40,000 shares.
The company issues another 25,000 shares exclusively to Shareholder A.
After the allotment:
Shareholder A: 85,000 ÷ 125,000 = 68%
Shareholder B: 40,000 ÷ 125,000 = 32%
Shareholder A’s percentage increases from 60% to 68%.
Shareholder B’s percentage decreases from 40% to 32%.
This illustrates disproportionate dilution.
How does a S$300,000 investment affect ownership at a S$900,000 pre-money valuation?
Pre-money valuation: S$900,000
New investment: S$300,000
Post-money valuation: S$1.2 million
New investor ownership:
S$300,000 ÷ S$1.2 million × 100 = 25%
Existing shareholders collectively retain 75%.
How does a higher valuation reduce dilution for the same investment?
Consider two companies each raising S$500,000.
| Item | Company A | Company B |
|---|---|---|
| Pre-money valuation | S$1 million | S$4 million |
| Investment | S$500,000 | S$500,000 |
| Post-money valuation | S$1.5 million | S$4.5 million |
| Investor ownership | 33.33% | 11.11% |
| Existing shareholders’ collective ownership | 66.67% | 88.89% |
Company B experiences substantially less percentage dilution because its negotiated pre-money valuation is higher.
How does an employee option pool affect fully diluted ownership?
A company has 100,000 issued ordinary shares.
The founder owns 70,000 shares.
An employee option arrangement provides for 20,000 additional shares upon exercise.
Current founder ownership:
70,000 ÷ 100,000 = 70%
Fully diluted founder ownership, assuming all 20,000 options are exercised into new ordinary shares:
70,000 ÷ 120,000 = 58.33%
The difference illustrates potential dilution from employee equity incentives.
How can convertible debt increase the number of shares issued?
A company has 200,000 ordinary shares.
A convertible lender has S$100,000 eligible for conversion.
The agreed conversion price is S$0.50 per share.
New shares on conversion:
S$100,000 ÷ S$0.50 = 200,000 shares
After conversion, the company has 400,000 shares.
Existing shareholders collectively retain 50%.
The lender receives 50%.
This example illustrates why conversion pricing can materially affect dilution.
How can a down round increase founder dilution?
A founder initially owns 100% of a startup.
The company raises S$1 million at a S$4 million pre-money valuation.
The investor acquires 20%.
The founder retains 80%.
Later, the company raises another S$1 million at a S$2 million pre-money valuation.
The second investor acquires one-third of the enlarged equity.
Assuming no other adjustments:
Founder ownership after the second round:
80% × 66.67% = approximately 53.33%
The founder has experienced substantial cumulative dilution.
Can dilution occur while the estimated value of a founder’s investment increases?
A founder owns 100% of a company valued at S$500,000.
The company receives S$500,000 in equity investment at that pre-money valuation.
The founder’s ownership falls to 50%.
The immediate post-money valuation is S$1 million.
The founder’s estimated investment value remains S$500,000.
Two years later, suppose the company is valued at S$4 million.
The founder’s 50% interest would then have an estimated value of S$2 million.
This illustrates how successful growth can outweigh percentage dilution.
How can an excessively low share issue price damage existing shareholders?
A company has 100,000 ordinary shares and an assumed equity value of S$1 million.
The company issues another 100,000 shares for S$100,000.
Assuming the original valuation remains otherwise unchanged, the simplified post-investment equity value becomes S$1.1 million.
Existing shareholders collectively retain 50%.
Their estimated collective economic interest becomes S$550,000.
The transaction therefore creates substantial economic dilution under the stated assumptions.
This is why the fairness of the subscription price should be considered carefully.
How does dilution affect a shareholder holding 10%?
A shareholder owns 10,000 out of 100,000 shares.
The company issues 50,000 additional shares to other investors.
The shareholder’s ownership becomes:
10,000 ÷ 150,000 × 100 = 6.67%
The shareholder experiences approximately 3.33 percentage points of dilution.
The relative reduction is approximately 33.33%.
How does dilution affect a company planning several future investment rounds?
A founder initially owns 80% of a company.
The company subsequently completes three rounds in which new investors acquire 10%, 20% and 15% of the enlarged equity, respectively.
Assuming the founder does not participate:
After Round 1:
80% × 90% = 72%
After Round 2:
72% × 80% = 57.6%
After Round 3:
57.6% × 85% = 48.96%
The founder’s ownership falls below 50%.
This demonstrates why cumulative dilution should be modelled before fundraising.
Frequently Asked Questions About Share Dilution in Singapore
Is share dilution always bad for shareholders?
No. Dilution may be justified where the company receives sufficient economic or strategic value.
Can share dilution happen without shareholders selling their shares?
Yes. This is a defining feature of ordinary dilution through additional share issuance.
Does dilution always reduce the number of shares held?
No. Existing shareholders may retain the same number of shares.
Can share dilution happen more than once?
Yes. Multiple investment rounds may cause cumulative dilution.
Can shareholders be diluted even if they originally paid more for their shares?
Yes. Historical subscription prices do not automatically prevent later dilution.
Can a profitable Singapore company experience share dilution?
Yes. Profitability does not prevent a company from issuing additional shares.
Can an unprofitable company experience share dilution?
Yes. Unprofitable companies may raise equity to finance operations or growth.
Can share dilution affect a Singapore company with S$1 paid-up capital?
Yes. The initial paid-up capital amount does not prevent future dilution.
Can a company experience dilution without raising cash?
Yes. New shares may be issued for qualifying non-cash consideration or under other properly structured arrangements.
Can dilution occur when a company issues shares to settle a debt?
Yes. If the settlement involves newly issued shares, existing shareholders may be diluted.
Can dilution occur through employee share incentives?
Yes. Newly issued employee shares can cause dilution.
Can share dilution be temporary?
Ownership percentages can change again through subsequent transactions, but dilution does not automatically reverse.
Can a shareholder recover a previous ownership percentage?
Potentially, by acquiring or subscribing for additional shares, subject to applicable rights and transaction terms.
Can a company issue shares at different prices during different investment rounds?
Yes, subject to applicable legal and corporate requirements.
Does a higher valuation guarantee that existing shareholders will benefit?
No. Valuations are estimates and may not translate into actual investment returns.
Can a shareholder be diluted even when the company receives valuable assets instead of cash?
Yes. The relevant consideration may be non-cash.
Can a shareholder be diluted by a convertible note?
Yes, when conversion results in newly issued shares.
Can a shareholder be diluted by an unexercised option?
An unexercised option may create potential dilution, but actual issued-share dilution generally depends on new shares being issued.
Is share dilution calculated using the number of shares or the amount invested?
Basic ownership dilution is calculated using relevant share numbers. Investment amounts and valuations are used to analyse the transaction’s economic effects.
Is a shareholder’s percentage ownership always equal to their voting power?
No. Voting rights may differ between share classes.
Is a shareholder’s percentage ownership always equal to their dividend entitlement?
No. Dividend rights may differ between share classes and depend on the applicable terms.
Can share dilution affect future fundraising negotiations?
Yes. Investors commonly examine current and fully diluted ownership structures.
Can share dilution affect founder motivation?
Potentially. Substantial dilution may affect founders’ long-term financial incentives.
Can share dilution make a private company harder to sell?
A complicated ownership structure may increase transaction complexity, although dilution alone does not necessarily prevent a sale.
Can dilution affect a shareholder’s investment even if the company grows?
Yes. The economic result depends on how much the company grows relative to the dilution experienced.
Should every Singapore startup maintain a dilution model?
A company expecting external investment, employee equity incentives or convertible financing would generally benefit from maintaining a reliable dilution model.
Should shareholders review the fully diluted cap table before investing?
Yes. This helps identify potential future ownership changes arising from outstanding equity-linked instruments.
What is the biggest mistake shareholders make when assessing dilution?
A common mistake is focusing only on the reduction in ownership percentage without considering valuation, subscription price, future funding needs and the potential economic value created by the investment.
What is the most important financial principle behind share dilution?
A smaller percentage of a more valuable company may be worth more than a larger percentage of a less valuable company.
However, shareholders should not assume that every dilutive transaction creates value.
The commercial terms and financial consequences must be assessed carefully.
Share Dilution Risk Assessment Checklist for Singapore Companies
Before accepting a dilutive investment, founders and shareholders should consider the following factors.
| Assessment area | Key question | Potential concern |
|---|---|---|
| Funding requirement | How much capital does the company genuinely need? | Raising unnecessary equity may create avoidable dilution |
| Company valuation | Is the proposed pre-money valuation reasonable? | Undervaluation may transfer excessive value |
| Subscription price | What price will investors pay per share? | Unfavourable pricing may create economic dilution |
| Immediate dilution | What ownership percentage will existing shareholders retain? | Unexpected reduction in ownership |
| Future dilution | How many additional rounds may be required? | Cumulative founder and investor dilution |
| Employee option pool | Is the proposed pool commercially justified? | Potential dilution from unused or excessive allocations |
| Convertible instruments | What shares may be issued upon conversion? | Hidden or underestimated future dilution |
| Anti-dilution clauses | Are preferential adjustments granted to investors? | Unequal consequences during down rounds |
| Financial projections | Can the investment realistically improve business value? | Dilution without sufficient commercial benefit |
| Cash runway | How long will the funding support operations? | Early need for further fundraising |
| Alternative financing | Could debt or retained earnings meet funding needs? | Unnecessary equity issuance |
| Investor contribution | Does the investor provide strategic value beyond cash? | Excessive ownership granted for limited benefits |
| Exit assumptions | How might future sale proceeds be distributed? | Ownership percentage may not reflect actual proceeds |
| Capitalisation records | Is the cap table accurate and current? | Miscalculated ownership and investor expectations |
| Legal documentation | Are investment and conversion terms properly documented? | Contractual uncertainty and disputes |
How Can Singapore Companies Develop a Sensible Share Dilution Strategy?
Should a company prepare a funding forecast before issuing equity?
Yes.
A realistic funding forecast helps management estimate how much capital is required and when additional financing may become necessary.
This reduces the risk of issuing excessive equity or raising insufficient funds.
Should founders model several future fundraising scenarios?
Yes.
A dilution model can compare different investment amounts, valuations and funding rounds.
It helps founders understand how their ownership may change over time.
Should companies consider investor quality as well as investment amount?
Yes.
A strategic investor may provide expertise, customer relationships, technology or access to new markets.
These contributions may justify dilution where they create meaningful commercial value.
Should companies avoid issuing shares at an unjustifiably low valuation?
Generally, yes.
A company should understand the economic consequences of its proposed subscription price.
An unjustifiably low valuation may create substantial economic dilution and potential disputes.
Should shareholders review outstanding options and convertible instruments before new fundraising?
Yes.
Outstanding equity-linked instruments can materially affect the fully diluted capital structure.
Ignoring them may result in inaccurate ownership projections.
Should founders focus on long-term company value rather than ownership percentage alone?
Yes.
Retaining a high percentage of a financially weak company may be less beneficial than owning a smaller percentage of a successful business.
However, long-term value creation should be supported by realistic assumptions rather than speculative projections.
When should a company seek professional advice about share dilution?
Professional advice may be particularly appropriate where the company is raising substantial investment, negotiating complex convertible instruments, creating employee equity incentives or considering transactions that materially change ownership.
Independent legal advice may also be necessary where shareholders dispute the fairness or purpose of a proposed share issue.
Conclusion: Understanding Share Dilution Before Raising Capital in Singapore
Share dilution is a normal feature of equity financing, particularly for Singapore startups and growing private limited companies.
It occurs when additional shares reduce the percentage ownership of shareholders who do not receive a proportionate allocation.
However, share dilution should not be confused with an automatic financial loss.
The actual economic effect depends on the company’s valuation, subscription price, investment proceeds, future business performance and the rights attached to the relevant shares.
For startup founders, the principal challenge is balancing the need for external funding against the long-term consequences of reduced ownership.
For investors, the challenge is understanding how future financing rounds, employee share options, convertible instruments and preferential investment terms may affect their economic interests.
For minority shareholders, dilution can create particular concerns where additional shares are issued at questionable valuations or under arrangements that disproportionately benefit other parties.
A sensible approach involves evaluating both immediate and potential future dilution.
Companies should maintain accurate capitalisation tables, model different investment scenarios, understand their fully diluted ownership and assess whether each proposed equity transaction creates sufficient commercial value.
The objective should not simply be to avoid dilution. It should be to ensure that any dilution is reasonable, transparent and justified by the value the company expects to receive.
How ACHI BIZ Can Assist Singapore Companies with Share Capital and Shareholding Administration
ACHI BIZ SERVICES PTE. LTD. is an ACRA Licensed Corporate Service Provider (CSP) providing corporate secretarial and compliance support to Singapore businesses.
Where a company proposes to issue additional shares or introduce new investors, ACHI BIZ can assist with relevant corporate secretarial administration, including:
-
Preparing and coordinating applicable corporate resolutions and share allotment documentation.
-
Assisting with relevant ACRA share allotment filings.
-
Supporting the maintenance of statutory corporate records.
-
Recording changes in issued shares and shareholder information.
-
Assisting with corporate secretarial compliance following changes in shareholding.
-
Coordinating relevant documentation with the company’s directors, shareholders and professional advisers.
For complex investment valuations, anti-dilution clauses, convertible instruments or shareholder disputes, companies should obtain appropriate independent legal, accounting or financial advice.
Related Articles
How Does Issuing New Shares Affect Existing Shareholders in Singapore? – FAQ Guide
Changing Share Capital After Incorporation in Singapore – FAQ Guide
#achibiz